
The “Big Five” Canadian banks offer investment funds and include Royal Bank of Canada, Toronto Dominion Bank (TD Canada Trust), Bank of Nova Scotia, Bank of Montreal and Canadian Imperial Bank of Commerce (CIBC). Let’s explore the best place for you to invest.
Latest News


S&P 500 hits record high, equals longest bull-run + MORE Aug 21st
The benchmark S&P 500 touched a record high on Tuesday and equalled its longest-ever bull-market run, as U.S. stocks rose on encouraging earnings reports and hopes that the United States and China could resolve their tariff dispute..... More »
Roughly half of Canadians financially insecure as debt confidence hits record low: report - Global News + MORE Jan 17th
Roughly half of Canadians financially insecure as debt confidence hits record low: report Global NewsPosthaste: Canadian confidence level plummets to new low as inflation set to hit 30-year high: Survey Financial PostThe Daily Chase: Key week for Bank of Canada; Survey reveals .... More »
Why the Haitians Should Stay + MORE Dec 27th
These longstanding residents are valuable assets to the U.S..... More »
Retirement planning advice for people who don’t use an advisor + MORE Jun 19th
Given that the financial media has long spent an inordinate amount of space on the topic of retirement, it seems the time was right for a retirement club devoted to Canadians on or near the cusp of retirement.
A few months ago, the Retirement Club for Canadians was launched by occ.... More »
From Pokemon cards to music royalties: Do alternative investments work? + MORE Oct 22nd
When some rare first-edition Pokemon trading cards went on sale three years ago, Adam O’Brien was hit with a wave of nostalgia. For the now 32-year-old, it was an irresistible offer that had the potential for value in the long run.
It was a bit of a gamble, spending $100,000 for thre.... More »
RRSP facts and guidance for 2017
– myownadvisor.ca
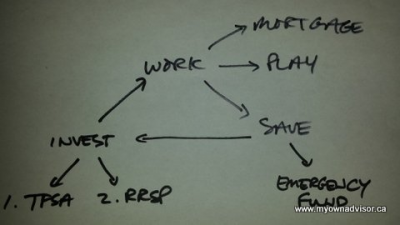 Save, invest, prosper with My Own Advisor.
The “RRSP season” is now in full swing but it’s important to know the ins and outs of this tax-deferred plan in order to optimize the use of this account for your financial situation. You’ll notice I didn’t write “time to buy RRSPs”. You don’t buy RRSPs friends…
Today’s post will remind you about some RRSP facts, why the RRSP is a powerful savings vehicle, why you might want to take advantage of it (and what to avoid), and share our longer term game plan for this account – for what that’s worth. Happy to hear all comments and critiques!
RRSP Fast Facts for 2017
When to contribute? The RRSP contribution deadline for the 2016 tax year is March 1, 2017. You should know this deadline is always 60 days after the end of the previous calendar year. This means RRSP contributions made in the first 60 days of 2017 can be applied to the 2016 tax year. (Note: we do this).
Who can contribute? There is no minimum age requirement to have an RRSP; a minor can set one up thanks to their parent or legal guardian…
Ten top RRSP questions answered
– macleans.ca
 (Shutterstock)
It’s that time of year again. RRSP season is upon us and before that March 1 deadline approaches, plenty of Canadians have questions about contributions, withdrawals and do’s and don’ts. Luckily, our experts have answered a lot of RRSP queries over the years. Are they a total waste of time? What happens if you over-contribute? How much money should you have in your account? Our friends at MoneySense have some answers.
Q: Are RRSPs ever a waste of time?
A: So, you have a Defined Benefit pension and don’t think RRSPs are worth your time? Depending on the situation (like if your spouse is out of work, or if they are in a lower tax bracket than you), contributing to an RRSP might be a great idea even if you have enough retirement savings. Here’s why.
Q: What are the differences between RRSPs and TFSAs?
A: The biggest differences are contribution limits, and how your money gets taxed upon withdrawal from the accounts. RRSP contributions are tax-deductible, whereas TFSA withdrawals are tax-free…

