
The best GIC rates in Canada for 2024 + MORE Jun 4th
Samsung Galaxy Z Fold7 “Sold Out” Across Major Cities, Production Ramped Up: Check Price And Top Features - NDTV Profit Jul 31st
Intel's worst day in 50 years: Stock trading at levels not seen in a decade - CNBC Television Aug 2nd
Tax write-offs that Canadians often get wrong Apr 14th
Buying ETFs in Canada Tool: The MoneySense ETF Screener Jan 2nd
Workspace of the Month: BMO’s New Toronto HQ Is Inside a Converted Department Store
– canadianbusiness.com
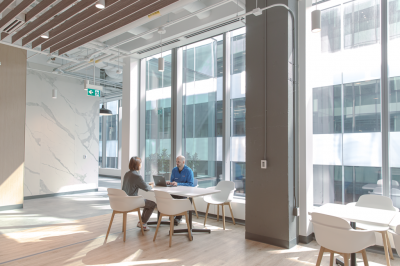 In 2016, George Della Rocca, BMO’s global head of corporate real estate, proposed to the bank’s executive team an unexpected location for its next downtown Toronto office: Ontario’s largest shopping mall, the Eaton Centre. Four floors, spanning 32,516-square-metres, in the mall had been vacated by the department store Sears, which closed its doors in 2014.
Della Rocca thought the space could be turned into the new headquarters for the 3,000 BMO employees working in personal and business banking. These departments were spread out between buildings all over Toronto’s core, and some leases were expiring. The spot appealed to Della Rocca since, unlike traditional office spaces, BMO would be able to “co-design” it with Cadillac Fairview, which operates the building. BMO could make significant changes, like adding an atrium, to suit its needs. Plus, with two subway stations in the mall, its location was close to public transit.
Related: Can Your Boss Actually Demand You Return to the Office?
BMO partnered with Cadillac Fairview to reimagine the space into a place where employees could collaborate across teams…
4 strategies for income splitting with a lower-income spouse
– moneysense.ca
What is the advantage when a husband buys stocks in his wife’s name? He works, and she has never worked.—Lynne
How income splitting with a lower-income spouse works
One spouse can buy stocks and other investments in the other spouse’s name. There can be tax or other implications depending upon the type of account.
1. Contributing to an RRSP
In the situation you’re asking about, Lynne, if the husband uses his income to contribute to a tax-sheltered account, there may be no tax issues. He can give his wife money to contribute to a registered retirement savings plan (RRSP), for example. But if she does not work, and never has, she probably does not have any RRSP room. RRSP room comes from earned income, like employment or self-employment income.
If she did have RRSP room, though, the husband could give her money to contribute to it without any tax implications. That said, if a person has no income, claiming an RRSP tax deduction would not be beneficial…
What is universal life insurance?
– moneysense.ca
Get personalized quotes from Canada’s top life insurance providers.All for free with ratehub.ca. Let’s get started.*Life Insurance QuotesTerm LifeWhole LifeThis will open a new tab. Just close the tab to return to MoneySense.
When the main objective is taking care of your loved ones after you’re gone, it pays to spend time figuring out how to care for them. That’s why you should familiarize yourself with the full slate of possibilities. For those looking for flexible premiums and the opportunity to accumulate wealth on a tax-deferred basis, universal life insurance can be a smart option…
DC plans once you retire: What do you do with them?
– moneysense.ca
 Two questions, two experts share their answers on what to do with a defined contribution (DC) pension plan when Canadians retire.
What to do with a DC plan when you’re about to retire
Ask MoneySense
My husband has an DC RPP through an insurance company and will retire within the next year. It is his only pension, although we have other non-registered investments. We are anticipating receiving $25,000-plus a year from this pension.
We are perplexed about who should manage the pension: Stay with the insurance company or transfer to our advisor with a big bank wealth management, who charges 1.25% in management fees? We have also considered self-directed management, using mostly GICs, which we realize may be only a short-term strategy.
There are a number of articles on the choices to converting to a LIF, but not on the choices for money management. (What about if people are satisfied with leaving their DC pensions with the big insurance companies? I would consider that to be the default option…

