
Poilievre says Canada will never be ’28th state’ of EU at Ontario rally - Global News Sep 20th
Bare trust rules for 2026: Do you actually have to file a T3? + MORE Nov 13th
Quebec premier stands firm on U.S. outreach after first meeting with Carney - The Globe and Mail Nov 15th
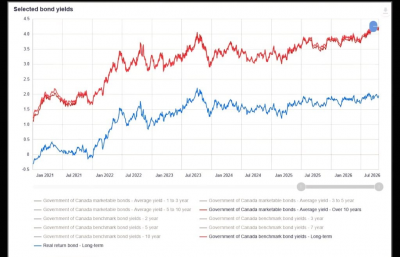
Should Canadian investors break up with their bond ETFs? + MORE Oct 29th
Ford government unveils big changes to OSAP. Critics say it offers no help for struggling students - Toronto Star + MORE Nov 12th
How to build a financial plan when your income is unpredictable
– moneysense.ca
I’ve been a freelance writer for the better part of 10 years, and admittedly am still figuring out my own financial strategy.
This past tax season, that reality hit me harder than ever. I was on the phone with my tax preparer, who asked not to be identified because his employer doesn’t allow public media commentary. After reviewing my finances and explaining how he’d arrived at the figure, he finally revealed the number I’d been waiting for: the amount I owed in federal and provincial taxes.
My stomach dropped. I knew I’d owe money—that’s just part of being self-employed—but the number didn’t match how financially insecure I felt. I’d always tried to do the “right” thing, setting aside roughly 30% of my income for taxes…
Does Wealthsimple want to add sports, politics to its new prediction markets product?
– moneysense.ca
But the first few weeks have some thinking Wealthsimple might have even bigger ambitions.
What is Wealthsimple really betting on?
When Charles Martineau, an associate professor of finance at the University of Toronto, and Marius Zoican, the Canada Research Chair in financial technology, each logged onto Wealthsimple’s Predict app, they found it displaying stakes in who will become the next James Bond, what the score will be at future football games, and who will win the 2028 U…

Here’s a round-up of news for Canadian investors this week.
Cargojet
Moneris
Barrick
Air Canada
Maple Leaf
Metro
Canadian Tire
Featured RRSP Accounts
featured
EQ Bank
Build your retirement savings with 1.50% interest, tax-deferred contributions and zero fees.
go to site
featured
Registered GIC rate
Earn a guaranteed 2.75% in your RRSP when you lock in for 1 year.
go to site
Best RRSP rates
See our ranking of the best RRSP accounts and rates available in Canada.
read now
Why trust us
MoneySense is an award-winning magazine, helping Canadians navigate money matters since 1999…
How to avoid these common RESP withdrawal mistakes
– moneysense.ca
Sandi Martin, a certified financial planner at Sandi Martin Financial Planning, said withdrawals can feel complicated because money can be taken from either of the two main parts of an RESP account. She said one component is the funds the account holder put in themselves, which can be withdrawn without a tax penalty. The other component consists of government grants or bonds and is taxable to the student upon withdrawal, along with any accumulated investment income.
“Sometimes it leads people to make a strategic error, which is, ‘Let’s take out from the non-taxable (portion) first,’” Martin said…
Why Gen Z is getting better at saying “I can’t afford it”
– moneysense.ca
 There was a time when telling your friends, “Sorry, I can’t afford it,” felt more uncomfortable than quietly putting a night out on your credit card.
A pricey birthday dinner? You went. A destination wedding that required a flight, hotel, and three new outfits? You just figured it out. A group trip you hadn’t budgeted for? Saying no meant admitting that money was the reason, and for many people, that’s enough to make them say yes anyway.
Gen Z is starting to change that. From talking openly about the cost of experiences to opting out when something isn’t in the budget, younger Canadians seem to be more and more willing to set financial boundaries—and even saying them out loud.
“I’d say in general, Gen Z is more vocal about boundaries, whether it’s their finances or in their career or their personal life, than probably any other generation,” says Jessica Moorhouse, an accredited financial counsellor and author of Everything but Money.
Why is Gen Z more comfortable saying no?
Part of the shift may simply be that this generation came of age with a louder voice…

