
Retirement planning getting you down? There are always smart ways to plan the financial aspects of your retirement.
Latest News


How to calculate the taxable amount for a cashed-in whole life insurance policy + MORE Apr 19th
Ask MoneySense
I cashed in my whole life insurance policy last year and received a T5 suggesting I have to pay tax on the full amount of my cash value. Is this correct? The cash surrender value was $27,000, I paid $28,000 in premiums, and they told me my pure cost of net insurance was $30,000, whate.... More »
When to break up with your financial advisor + MORE Nov 4th
TORONTO – When Deborah Ison decided to break up with her financial advisor last year, investment performance had nothing do with her decision.
The 45-year-old human resources project manager from Burlington, Ont., was in the midst of a divorce and went to her advisor with pressing questions about .... More »
Stock news for investors: First Quantum profit jumps, Intact earnings fall Aug 1st
Here’s a round-up of news for Canadian investors this week.
Intact
First Quantum
CGI
Algoma
Power Corp
Spin Master
Featured RRSP Accounts
featured
EQ Bank
Build your r.... More »
How to retire at 55 on $55,000 a year + MORE Jan 7th
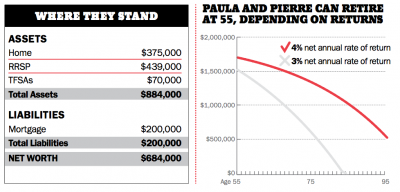
Paula Lorimer and husband Pierre Sopel save $30,000 annually. They hope to retire at age 55 with a net annual income of $55,000.
The current situation
Paula Lorimer, 40, is a psychologist living in Montreal. Right now, Paula is self-employed but is looking forward to changing gears at age 55. “Iâ€.... More »
Can Power of Attorney claim a fee? + MORE Jun 26th
“Image courtesy of Grant Cochrane/ FreeDigitalPhotos.net”.
Q: My wife’s sister has been diagnosed with Alzheimer’s disease, and is now living in a retirement home with some assistance. She named my wife Power of Attorney. Can my wife claim a fee for looking after her and her affairs?.... More »
When smart people do dumb things with money
– moneysense.ca
Investors can a learn a lot from pension funds, particularly when it comes to diversification, risk management and long-term thinking. But it seems professional money managers are not immune from the behavioural challenges that plague retail investors.
Doug Cronk, who writes a useful blog called Institutional Investing for Individual Investors, recently pointed me to a couple of industry articles that make it clear the pros are just as human as the rest of us. (I interviewed Doug last fall for an article called “Invest like a pension fund manager” in Canadian Business.)
In a February article in Pensions & Investments, a strategist explains that many pension funds have an investment plan that calls for them to increase their allocation to bonds when their plan is well funded. This is what investors might call “taking risk off the table”: the idea is that if equity markets have been strong and you believe you’re comfortably on track to meet your goals, you can afford to reduce the risk in your portfolio…
Doug Cronk, who writes a useful blog called Institutional Investing for Individual Investors, recently pointed me to a couple of industry articles that make it clear the pros are just as human as the rest of us. (I interviewed Doug last fall for an article called “Invest like a pension fund manager” in Canadian Business.)
In a February article in Pensions & Investments, a strategist explains that many pension funds have an investment plan that calls for them to increase their allocation to bonds when their plan is well funded. This is what investors might call “taking risk off the table”: the idea is that if equity markets have been strong and you believe you’re comfortably on track to meet your goals, you can afford to reduce the risk in your portfolio…
Tax-free Savings Accounts Offer Multiple Advantages for Canadians
– rhondasherwood.com
 Tax-free Savings Accounts (TSFAs) offer flexibility to Canadian savers. While a Registered Retirement Savings Plan (RRSP) is designed to put aside funds for retirement, a TFSA is a vehicle which can be used to put money aside for any purpose. If you are looking for a way to put money aside for a big ticket item like a special vacation, a car, home or a cottage, depositing funds into a TFSA can be a great choice.
The types of things that a person may want to save money for will vary, depending on his or her own personal goals. As of January 1, 2013, a taxpayer can contribute up to $5,500 per year into a TFSA. Any unused contribution room is carried forward, which means that someone who has more income in later years can make higher contributions to his or her TFSA without incurring a penalty.
Withdrawing Funds from Tax-free Savings Accounts
Funds which are withdrawn from the plan can be replaced later without having an impact on a person’s allowable contribution room.
Here’s an example of how this provision works: Laura contributes $5,500 per year for 10 years into a TFSA and earns investment income on the money held in the plan…

