
Obtaining a mortgage or secured line of credit in Canada at the best rates is often a daunting task. We can help! Read the articles below for more info.
Latest News


How the Bank of Canada’s benchmark rate impacts your finances + MORE Mar 7th
The Bank of Canada (BoC) held its benchmark interest rate at 5% on March 6, marking the fifth consecutive time it has left the rate unchanged. Economists widely expect the BoC to lower its rate at some point in 2024, as inflation falls and the Canadian economy weakens. However, in its March rate ann.... More »
Over half of Canada’s self-employed workers face income shortfalls—here’s what that means Nov 6th
There are over 2.7 million self-employed workers in the country, according to Statistics Canada. Although that number has grown over the last year, higher numbers haven’t meant an improvement in self-employment finances.
Alberta-based non-profit credit counselling agency Money Mentors partnered.... More »
10 up and 3 down, unintended consequences! + MORE Sep 22nd
LOTS OF MOVEMENT IN MORTGAGE RATES
Sounds like a football play. But I’m not talking about football even though the NFL season just started and my Buffalo Bills won their first two games. I’m referring to how many times the Bank of Canada’s (BoC) Governor, Tiff Macklem, has changed the Overn.... More »
Fixed mortgage rates in Canada resume their decline amid economic volatility Feb 5th
After a short-lived upswing in bond yields last month that nudged some fixed mortgage rates higher, lenders are once again bringing them back down..... More »
Why Canadian investors should avoid MLPs Jan 20th
For better or worse, a sizable group of Canadian investors still screens prospective investments by dividend yield. When that search expands beyond Canadian stocks, it often leads into parts of the U.S. market that look attractive on the surface but are poorly understood.
Common examples include .... More »
How much does a 1996 house cost today?
– moneysense.ca
Housing prices are much higher today, but interest rates are significantly lower. So, has housing affordability actually changed? To appreciate the impact of inflation let’s take a look at, as an example, the cost of homes today versus 10 or 2o years ago in Toronto.
According to the Toronto Real Estate Board’s historic home prices for Toronto, houses cost, on average:
According to the Toronto Real Estate Board’s historic home prices for Toronto, houses cost, on average:
Year
Average Price
Average 5-year mortgage rate
20% down payment required
2016
$739,382*
2.33%
$147,876
2006
$351,941
5.25%
$70,388
1996
$198,150
9%**
$39,630
*Based on April 2016 data
**Based on BoC prime + 2%
But to really compare these costs, let’s factor out inflation. Using the Bank of Canada’s inflation calculator, here’s what homes and mortgage payments would look like in today’s dollars:
Year
Average Price
In today’s $
20% down in today’s $s
% change in those years
2016
$739,382*
$739,382
$147,876
0%
2006
$351,941
$413,498
$82,670
17.49%
1996
$198,150
$286,614
$57,232
44…
Being hooked on debt has long-term consequences
– moneysense.ca
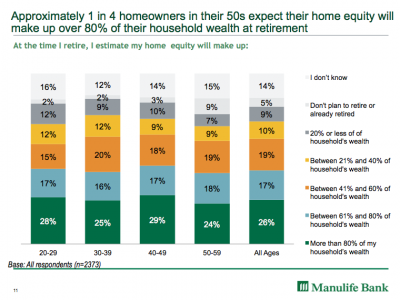 Hooked on debt. It’s an apt description for the rising debt-to-income levels currently seen in Canada and a new survey by Manulife Bank highlights there’s a high price to our debt dependency—a cost that goes far beyond the low interest rates you see posted online.
Impact on those approaching retirement
One of the biggest contributors to our increased debt-load are rising housing costs. These increased shelter costs make it far more difficult for homeowners to balance paying down their mortgage, while saving for retirement and managing day-to-day expenses, explains Rick Lunny, president and CEO of Manulife Bank of Canada.
According to the new Manulife Bank Canada survey, 37% of homeowners were “caught short” at least once in the past year—meaning they didn’t have enough money to cover their expenses. Worse, only 40% of Canadians are confident that they are saving enough for retirement. “For many, not saving enough means relying on their home equity as a significant portion of their retirement package,” says Lunny…
A rising housing market lifts builders, home goods retailers
– canadianbusiness.com
NEW YORK, N.Y. – A new report from the U.S. that showed Americans are snapping up homes at a pace not seen since the housing bust-fueled recession pushed the trading of shares of all companies affiliated with the sector into overdrive Tuesday.
The Commerce Department reported that new home sales jumped 16.6 per cent last month to a seasonally adjusted rate of 619,000, up from a revised total of 531,000 in March. A mix of steady job gains and historically low mortgage rates are bringing more Americans back into a housing market even as rising prices put many properties out of range.
Sales of existing homes, which make up 90 per cent of the housing market, rose in April for a second straight month to an annual pace of 5.45 million, a figure consistent with a solid economy.
That’s the highest level since January 2008, when the U.S. was teetering into the worst economic downturn since the Great Depression.
While there has been talk about the possibility of a second housing bubble bursting as it began to do in the U…
The Commerce Department reported that new home sales jumped 16.6 per cent last month to a seasonally adjusted rate of 619,000, up from a revised total of 531,000 in March. A mix of steady job gains and historically low mortgage rates are bringing more Americans back into a housing market even as rising prices put many properties out of range.
Sales of existing homes, which make up 90 per cent of the housing market, rose in April for a second straight month to an annual pace of 5.45 million, a figure consistent with a solid economy.
That’s the highest level since January 2008, when the U.S. was teetering into the worst economic downturn since the Great Depression.
While there has been talk about the possibility of a second housing bubble bursting as it began to do in the U…
What to do with your extra cash
– moneysense.ca
 (Getty Images)
Q: I am turning 30 this year and make around $60,000 a year and was wondering what the best thing to do with some extra money is? I have $10,000 saved in an emergency fund sitting in a high-interest bank account at my bank, so I am covered in case of emergency. Is this the best place for this?
On top of that I have around $5,000-$10,000 extra I am looking to use to start investing and was wondering where it should be put. I have no debt other than a mortgage for $90,000 with 10 years left at 3% which I am already paying an extra 10% per payment towards. I have an RRSP through my work, but I am only contributing 3% in order to max out their matching 3%. I am doing the minimum because it has a high MER of about 2.75%.
I was thinking of starting a Couch Potato Portfolio via a robo-advisor site or inside of a TFSA as I have never contributed to a TFSA. I have never done any investing other than RRSPs through my jobs so I could use some advice to ensure I am using my money wisely…

