
Weekly mortgage digest: Which big banks just dropped fixed rates? + MORE Jul 11th

Home Capital Was Hours Away From Collapse: Report + MORE May 15th
Q1 Lender Earnings: The Recovery is Underway + MORE May 22nd

What to do about your debt and mortgages after the interest rate hike Jan 29th
How Your Cell Phone Can Keep You From Getting the Lowest Mortgage Rate + MORE Nov 27th
 Even George R.R. Martin couldn’t dream up the calamity that would befall us if Canada tightened mortgage rules.
That about sums up the sentiment espoused by Will Dunning, chief economist of Mortgage Professionals Canada on Tuesday.
In a stunning news release, he said that tightening lending conditions would have “tragic” consequences for the Canadian economy. He went on to say there’s “insufficient proof that a bubble exists” and that there was none of a “speculative mindset.”
Dunning also said there’s “no evidence of an increase in risk by borrowers or lenders.”
Every one of those statements flies in the face of recent expert analysis on the Canadian housing market.
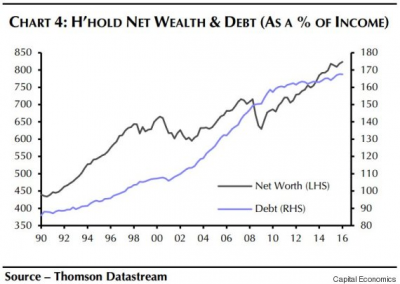
Earlier this month, Capital Economics issued a report that said Canada’s housing bubble would “end in tears.”
Economist Paul Ashworth blamed house price growth on people racking up more and more debt, a trend that was “fuelled by relaxed lending standards,” he said.
“The decline in interest rates and interest servicing costs allowed households to expand their debt without increasing the proportion of their incomes needed to meet their overall debt service obligations,” Ashworth added…
Mortgage Career: Educators’ Financial Group
– canadianmortgagetrends.com
This mortgage loophole puts us at risk
– moneysense.ca
According to their analysis the six big banks would lose nearly $12 billion while CMHC and other mortgage insurers would be on the hook for as much as $6 billion, but only if Canada were to experience a U.S.-style housing crisis where home values were to fall by as much as 35%.
Apparently, the report was a stress-test: a number-crunching exercise to reveal the worst-case scenario; situations that might occur, like a sharp increase in interest rates or massive job layoffs. But one Toronto mortgage broker is far less concerned about less than probable extreme market corrections.
The five-year fixed loophole
Based out of Toronto, Calum Ross works with high net worth clients as a dually licensed wealth advisor (with his MBA) and as an independent mortgage broker. Over the years, Ross has grown more and more concerned with mortgage qualification rules and how loopholes could contribute to over-leveraged homeowners and a potentially catastrophic future fall-out…

