
The “Big Five” Canadian banks offer investment funds and include Royal Bank of Canada, Toronto Dominion Bank (TD Canada Trust), Bank of Nova Scotia, Bank of Montreal and Canadian Imperial Bank of Commerce (CIBC). Let’s explore the best place for you to invest.
Latest News

The Triple Threat of a Triple Bottom Line Dec 19th
If you hadn’t noticed already, Canada’s workforce is changing. It’s expected that by 2030, nearly 30% of it will be made up of Gen Z employees—bringing to the office greater expectations for social good and the triple bottom line. Among mental health, climate change and other social issues i.... More »
House rich, cash poor: When a reverse mortgage might make sense Jul 15th
Reverse mortgages were at one time considered the Wild West of financial products, associated with aggressive and even predatory sales tactics targeting seniors in the United States. Fairly or not, that reputation has instilled some wariness in Canada, where regulations have long been more stringen.... More »
The best GIC rates in Canada for 2025 May 25th
GIC comparison tool
Find the best and most up-to-date GIC rates in Canada using the comparison tool below. Plus, use the filters to assess your estimated rate of return based on the size of your balance.
Why trust us
MoneySense is an award-winning magazine, helping Canadians navigate m.... More »
New active U.S. ETFs for Canadian investors—are these funds worth your money? May 1st
Despite U.S. President Donald Trump’s trade wars and tariffs on key partners, including Canada, the U.S. asset management industry continues to view Canadian investors as an attractive market for actively managed exchange-traded funds (ETFs).
In October 2024, Capital Group, best known for manag.... More »
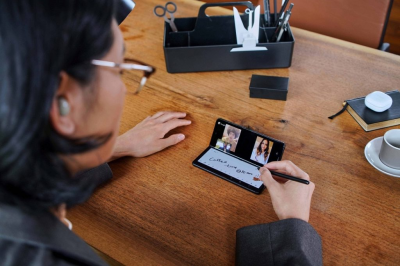
Innovative Devices are Transforming a Regular Day’s Work in the Financial Services Industry Dec 23rd
When COVID-19 hit, the pace of digital adoption within the financial services industry was accelerated practically overnight. Employees needed a way to stay connected and productive away from the office and turned to the latest digital tools and technologies to make this a reality. Now, there’s no.... More »
How to calculate capital gains and losses on rental property
– moneysense.ca
Q. I am selling my rental property, which I lived in for six years before renting it out the last five years. I do not own another home and I am selling this one for less than market value because some horrible renters caused the property to become run down. My mortgage principal is $263,000 and I am selling privately (to avoid real estate commission costs) for $325,000. What do I need to know in regards to capital gains reporting and taxes?
– Chris
A. When you convert a home that is your principal residence into a rental property, this is considered a change in use. You are deemed to dispose of the property at the fair market value at that time, and immediately reacquire it. Future capital gains may then apply based upon subsequent growth in the property’s value.
Under subsection 45(2) of the Income Tax Act, it’s possible to continue treating a principal residence converted to a rental property as your principal residence for up to four years. There are, however, several conditions:
1) You must report the subsequent rental income;
2) You cannot claim depreciation (capital cost allowance) on the property as a tax deduction;
3) You cannot designate another property as your principal residence;
4) You must be a Canadian resident…
– Chris
A. When you convert a home that is your principal residence into a rental property, this is considered a change in use. You are deemed to dispose of the property at the fair market value at that time, and immediately reacquire it. Future capital gains may then apply based upon subsequent growth in the property’s value.
Under subsection 45(2) of the Income Tax Act, it’s possible to continue treating a principal residence converted to a rental property as your principal residence for up to four years. There are, however, several conditions:
1) You must report the subsequent rental income;
2) You cannot claim depreciation (capital cost allowance) on the property as a tax deduction;
3) You cannot designate another property as your principal residence;
4) You must be a Canadian resident…

