
Affordability tips for first-time home buyers to securing a mortgage Nov 2nd
Can a non-resident open an investment account in Canada? Sep 21st

Stock news for investors: Canadian Natural boosts quarterly dividend after massive Q4 profit Mar 7th
How does a mortgage inside an RRSP work? + MORE Jun 3rd
How to boost your retirement income by 50% + MORE Nov 18th
Best way to invest a large sum of money
– moneysense.ca
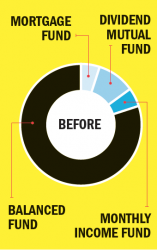
Moyra Thompson, 60, is retired and her $600,000 mortgage-free house is up for sale. “I want to sell before boomers flood the market with homes,” says Moyra, who receives $2,100 a month from two small pensions and will start collecting CPP at age 65. Right now, her $150,000 portfolio is invested in bank mutual funds with an overall management expense ratio (MER) of 1.9%, split evenly between fixed income and equities—but even with an additional $600,000 Moyra is concerned her money won’t last into her 90s. “I’ll need $15,000 net a year from my portfolio. I’m not sure the 50% fixed income and 50% equity split will give me that.”
Certified financial planner Chris Stephenson of Steadyhand Investment Funds in Vancouver says that if Moyra’s goal is to withdraw $15,000 annually from a $750,000 portfolio (an extraction rate of 2%), she’ll have no problems. In fact, this is easily achievable with her current asset mix of 50% stocks and 50% fixed income, and Stephenson sees no reason to change this…
5 Ways to Become Debt Free In 10 Years
– walletpop.ca
1. Decrease your interest rates and consolidate
Interest rates are at their lowest in the history of time. Consolidate as much of your debt as possible at the cheapest rate. Re-mortgage or consolidate your debt on a low interest line of credit to save a ton. Try to get your interest rate down to three per cent or lower. This will help you save tens of thousands in interest over the next 10 years. Interest rates aren’t expected to jump higher in the next few years due to the economy, and it is easier to pay more off at lower rates…
Average expected retirement age rises to 63: Poll
– moneysense.ca
.tab-nav li.menu-item a{
padding: 22px 18px;
}
}
MONTREAL – A new survey suggests many Canadians are pessimistic about their financial futures and expect to work longer than originally planned before retiring.
According to the survey, released by the Canadian Payroll Association, three-quarters of working Canadians polled reporting having put aside less than 25 per cent of the money they expect to need in retirement.
And it says less than half of people even 50 and older have reached that threshold.
The survey, the association’s seventh annual to mark National Payroll Week, also found that 35 per cent of respondents expect to work longer.
According to the survey, the average expected retirement age has risen to 63 years from 58 five years ago.
More than one in five employees surveyed said they will need to work four years or more than they originally expected before retiring, citing a lack of sufficient savings as the main reason…

