
First-Ever Green Star Discovered, Scientists Take Step Towards "Schrödinger’s Cat In Real Life", And Much More This Week - IFLScience + MORE Oct 17th
Priority Pass: Benefits & Pricing Change coming in January 2027 & Catch up on This Week in RWRDS (RWRDS Daily Update November 16) Nov 16th
Dark web monitoring: Keeping your identity safe + MORE Nov 5th
Is the RBC British Airways Visa Infinite worth it? We did the math Oct 19th
Chexy x Rogers: Earn 1% extra cash back on Chexy payments made with select Rogers Mastercards + MORE Nov 11th
What to do about your mortgage when you get a divorce in Canada
– moneysense.ca
 A divorce can leave you holding a mortgage that was approved on two incomes. Who stays in the home? Can they qualify on their own? What does it cost to change the loan? What are the mortgage rules in the context of divorce in Canada? Several questions need answering and shape what happens next.
The answers often come down to details people only learn once a separation is underway, such as how the mortgage stress test applies when one name comes off the loan, or how the Home Buyers’ Plan works when a marriage ends.
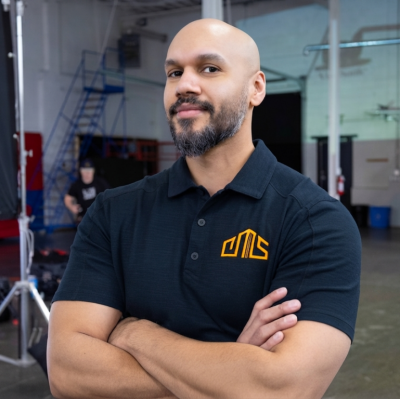
Neil Drepaul, a mortgage broker, director and co-owner of Canadian Mortgage Services, answered 10 questions for MoneySense to work out those details.
Neil Drepaul (Supplied)
Drepaul has 14 years of experience in the Canadian mortgage and lending industry and works in the family business his father founded in 1988. His areas of expertise include mortgage rates and renewals, lending rules, self-employed borrowers, refinancing and debt consolidation, and the broader economic factors that can affect Canadians’ mortgages and access to credit…

