
Young Canadians sue CPP Investments over climate risks + MORE Oct 30th

Say Good-bye to Foot Pain: Kick Your Bunion to the Curb Aug 26th

Capital gains taxes explained Nov 11th

Want to save money on auto insurance? Buy winter tires, say experts Oct 22nd
How do the RRSP contribution carry forward rules work? + MORE Jun 9th
Toronto stock index makes meagre gain, as energy and gold sectors weigh
– canadianbusiness.com
The S&P/TSX composite index added 5.83 points to 16,004.40. Valeant Pharmaceuticals Intl. Inc. (TSX:VRX) and Shopify Inc. (TSX:SHOP) had some of the biggest advances, up more than six per cent and nearly four per cent respectively at the closing of markets.
In New York, the Dow Jones industrial average gained 72.09 points to 23,430.33. The S&P 500 index edged up 3.29 points to 2,582.14 and the Nasdaq composite index advanced 7.92 points to 6,790.71.
The Canadian dollar was trading at 78.17 cents US, down 0.06 of a U.S. cent.
In commodities, the January crude contract was down 29 cents at US$56.42 per barrel and the December natural gas contract declined five cents to US$3.05 per mmBTU.
The December gold contract fell US$21.20 to US$1,275.30 an ounce and the December copper contract added three cents to US$3…
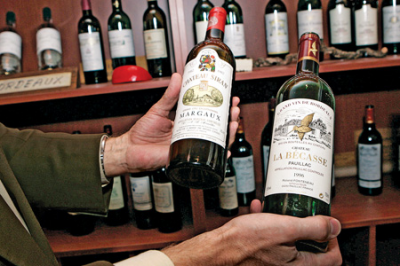
Q. In the 1980s, I bought a number of bottles of wine that I kept in my cellar. I’ve now put this wine up for auction, and it will fetch over $10,000. However, I have no records of the original purchases, and no memory of what I paid for the wine, although it was certainly a lot less. How do I handle the reporting of capital gains on the sale of the wine? – Ken M. Toronto
Hi, Ken. That’s a good question. For U.S.citizens, green card holders and those who are considered resident aliens under the U.S. Tax Code, sales from collectibles including bottles of wine are taxed a 28% capital gains rate, plus of course an additional 3.8% Net Investment Income Tax if you have a high income.
Assuming you live in Canada, you would receive credit for any taxes you pay to Canada Revenue Agency on the income. On the Canadian side, because the wine is listed as personal property, the original cost is assumed to be $1.000 (Cdn.). That would be your starting point.
Since Canadian taxpayers are required to keep books and records in order to determine their tax liability, you would need to find some sort of documentation to support a higher cost…
How mutual fund investors are being left out of the pot stock rally
– theglobeandmail.com
 Author Moshe Milevsky makes his case to bring back a financial instrument from the past.
SPEED READER
Book: King William’s Tontine: Why the Retirement Annuity of the Future Should Resemble its Past
Author: Moshe A. Milvesky
Publisher: Cambridge University Press
Price: $56.43 for 257 page hardcover ($39 for the paperback)
WHO IS IT FOR? Anyone interested in discovering new ways to help us fund retirement—and if you love history, all the better.
WHAT IS A TONTINE? Part annuity, part lottery, and part hedge fund, the tontine—which recently celebrated its 360th birthday—offered a lifetime of income that increased as other members of the tontine died off and their money was distributed to survivors. The tontine is a slightly macabre concept that involves the pooling of investments in such a way that those who die end up subsidizing those who keep living.
Tontines: The retirement plan of the future?
WHY WE LIKE IT. Who would have guessed that a tontine financing scheme invented by a 17th Century Italian businessman might hold the key to retirement security for today’s workers? The investment takes its name from Lorenzo de Tonti, an exiled Neapolitan banker living in France who, in 1653 conceived of a plan to replenish the royal treasury, depleted by the Thirty Years’ War…
A TFSA to protect against an apocalypse
– moneysense.ca
Trevor Bonnici
AGE: 47
PLACE: Toronto
TFSA TOTAL: $47,895
STRATEGY: a portfolio that protects against hyperinflation and maintains his purchasing power
TFSA Holdings
Gold
25%
Mawer Global Bond Fund
35%
1 to 5-year TIPS VTIP ETF
10%
Polar Long/Short Fund (POL202)
(small- to mid-cap Cdn. equities)
5%
GIC ladder
(self-built in a self-directed account with 3rd party GICS that are CDIC-insured)
TOTAL
100%
Trevor Bonicci is 47-years old and works in the financial industry in Toronto. He has one aim with the $47,895 TFSA portfolio he put together recently, and that’s to protect his purchasing power at retirement. He’s even okay if he makes a zero real rate of return, as long as he’s protected against hyperinflation of the loonie and other currencies as well. “Preservation is the goal for my portfolio,” says Trevor who admits his approach is a bit unorthodox.
Trevor’s goal is a simple one. “I just want to ensure that what I hold today will be able to have the same purchasing power 30 years from now with as little risk as possible,” says Trevor…

