
The “Big Five” Canadian banks offer investment funds and include Royal Bank of Canada, Toronto Dominion Bank (TD Canada Trust), Bank of Nova Scotia, Bank of Montreal and Canadian Imperial Bank of Commerce (CIBC). Let’s explore the best place for you to invest.
Latest News

The best high-interest savings accounts in Canada for 2024 + MORE May 21st
Save
The best high-interest savings accounts in Canada for 2024
Here are the accounts offering the highest interest rates and lowest fees.
Compare now
Tap the button for more details.
W.... More »
Toronto real estate board calls on Ottawa to revisit mortgage stress test - 680 News Feb 6th
Toronto real estate board calls on Ottawa to revisit mortgage stress test 680 NewsToronto Real Estate Board urges OSFI to 'revisit' stress tests BNNBloomberg.caToronto home sales expected to rebound, but mortgage rules need review: TREB The Globe and MailToronto area.... More »
Understanding Bitcoin and the frenzy behind the digital currency + MORE Dec 8th
CALGARY _ The bitcoin frenzy shows no sign of letting up, with the price of the digital currency topping US$17,000 Friday and bitcoin futures set to start trading on Sunday. Here’s a look at what bitcoin is and why there’s so much excitement around it.
So what is bitcoin?
It’s a fa.... More »
Carney going to New York this week to meet with business leaders, court investment - CTV News May 24th
Carney going to New York this week to meet with business leaders, court investment CTV NewsSee more headlines & perspectives on Google News.... More »
Mortgage broker vs. bank—which will save you more money? Jun 1st
Choosing a mortgage broker or a bank for your home loan will likely influence which mortgage you end up with. On top of that, there are pluses and minuses to both, as we detail in the table below. Before we dive into which may best suit your financial situation, let’s look at the differences betwe.... More »
New Justice Department policies encourage more prosecutions of corporate executives
– canadianbusiness.com
WASHINGTON – The Justice Department issued new guidance to its prosecutors on Wednesday, aimed at encouraging more white-collar criminal cases against corporate executives.
The new policies come amid persistent criticism that the Justice Department, even while negotiating multi-billion-dollar settlements with large banks, has not been aggressive in prosecuting individuals for financial misconduct — including after the mortgage crisis that devastated the U.S. economy.
The policy changes were outlined in a memo issued to Justice Department attorneys and to the FBI, and Deputy Attorney General Sally Yates was expected to discuss the issue in a speech Thursday at New York University’s law school.
Though it’s not clear whether the new policies will actually result in additional prosecutions, they reflect concerns that the department could be doing more to hold individual, high-level executives accountable.
“Regardless of how challenging it may be to make a case against individuals in a corporate fraud case, it’s our responsibility at the Department of Justice to overcome these challenges and do everything we can to develop the evidence and bring these cases,” Yates will say in her speech, according to excerpts provided by the Justice Department…
The new policies come amid persistent criticism that the Justice Department, even while negotiating multi-billion-dollar settlements with large banks, has not been aggressive in prosecuting individuals for financial misconduct — including after the mortgage crisis that devastated the U.S. economy.
The policy changes were outlined in a memo issued to Justice Department attorneys and to the FBI, and Deputy Attorney General Sally Yates was expected to discuss the issue in a speech Thursday at New York University’s law school.
Though it’s not clear whether the new policies will actually result in additional prosecutions, they reflect concerns that the department could be doing more to hold individual, high-level executives accountable.
“Regardless of how challenging it may be to make a case against individuals in a corporate fraud case, it’s our responsibility at the Department of Justice to overcome these challenges and do everything we can to develop the evidence and bring these cases,” Yates will say in her speech, according to excerpts provided by the Justice Department…
Harper’s RESP pledge: Good news, missed opportunity
– moneysense.ca
Prime Minister Stephen Harper recently announced that, if his party is re-elected, it would enrich the additional Canada Education Savings Grant (CESG) as a way “to help hard-working families save for their children’s post-secondary education.” There seems to be some confusion about what exactly this means, and what effect it will have.
Most Canadians seem to be aware of Registered Education Savings Plans (RESPs). RESPs allow parents of kids under the age of 18 to invest after-tax dollars into a fund to pay for their post-secondary education. One of the main advantages of investing in RESPs is that the federal government (and some provincial governments) provides matching funds, up to a maximum, called the Canada Education Savings Grant. There are two components to the CESG.
The basic CESG, which has not changed, allows all parents, regardless of income, to get a 20 per cent matching grant on all contributions up to $2,500. So every parent in Canada who has a child under the age of 18, and opens an RESP and invests money into that RESP, gets an additional contribution paid for by taxpayers…
Most Canadians seem to be aware of Registered Education Savings Plans (RESPs). RESPs allow parents of kids under the age of 18 to invest after-tax dollars into a fund to pay for their post-secondary education. One of the main advantages of investing in RESPs is that the federal government (and some provincial governments) provides matching funds, up to a maximum, called the Canada Education Savings Grant. There are two components to the CESG.
The basic CESG, which has not changed, allows all parents, regardless of income, to get a 20 per cent matching grant on all contributions up to $2,500. So every parent in Canada who has a child under the age of 18, and opens an RESP and invests money into that RESP, gets an additional contribution paid for by taxpayers…
August 2015 Dividend Income Update
– myownadvisor.ca
Learn, save, invest and prosper by subscribing to My Own Advisor.
Welcome to my latest dividend income update. For those of you new to these posts on my site, every month I discuss my approach to investing focusing on dividend paying stocks and how reinvesting the dividends paid from the Canadian companies we own are helping us reach financial freedom.
Although I’m a fan of low-cost Exchange Traded Funds (ETFs) to diversify my portfolio more going forward, I focus on holding and DRIPping dozens of brand name Canadian companies in our non-registered accounts and Tax Free Savings Accounts (TFSAs).
To recap, here is our simple approach to dividend investing:
Welcome to my latest dividend income update. For those of you new to these posts on my site, every month I discuss my approach to investing focusing on dividend paying stocks and how reinvesting the dividends paid from the Canadian companies we own are helping us reach financial freedom.
Although I’m a fan of low-cost Exchange Traded Funds (ETFs) to diversify my portfolio more going forward, I focus on holding and DRIPping dozens of brand name Canadian companies in our non-registered accounts and Tax Free Savings Accounts (TFSAs).
To recap, here is our simple approach to dividend investing:
We only buy established companies that have a modest to long history of paying dividends. Many of the stocks we own have paid dividends for over 100 years.
We reinvest all the dividends paid by these companies so whenever possible, so money that makes money will make retirement money.
We diversify our stock holdings by buying new companies…
The Bush Growth Plan
– online.wsj.com
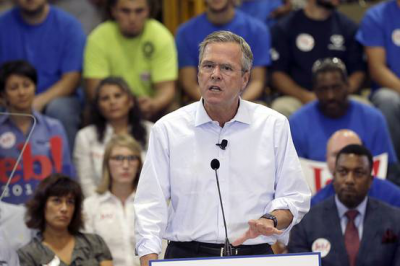 Tax reform that would cut rates and unleash business investment.
S&P cuts Brazil’s sovereign debt to ‘junk’ status, upping pressure on Rousseff to find way out
– canadianbusiness.com
RIO DE JANEIRO – The Brazilian government’s sovereign debt rating was cut Wednesday to “junk” status by one of the major credit agencies, ratcheting up pressure on President Dilma Rousseff to find a way out of an economic and political crisis.
Standard & Poor’s said in a note that Brazil’s hard-fought investment grade status that it held for seven years was gone and that its outlook on the country was negative, just as the nation enters recession and is expected to see an even worse 2016.
That means that it will be far more expensive for the Brazilian government to tap international credit markets and that much investor money, such as mutual funds that only plow money into investment-grade nations, will automatically be yanked out of the country.
S&P said that extreme political challenges for Rousseff “have continued to mount, weighing on the government’s ability” to shore up its finances as promised.
The downgrade comes on the heels of Rousseff submitting a budget to Congress that already had a built-in deficit of about $10 billion, meaning she tossed to legislators the burden of figuring out where to make cuts…
Standard & Poor’s said in a note that Brazil’s hard-fought investment grade status that it held for seven years was gone and that its outlook on the country was negative, just as the nation enters recession and is expected to see an even worse 2016.
That means that it will be far more expensive for the Brazilian government to tap international credit markets and that much investor money, such as mutual funds that only plow money into investment-grade nations, will automatically be yanked out of the country.
S&P said that extreme political challenges for Rousseff “have continued to mount, weighing on the government’s ability” to shore up its finances as promised.
The downgrade comes on the heels of Rousseff submitting a budget to Congress that already had a built-in deficit of about $10 billion, meaning she tossed to legislators the burden of figuring out where to make cuts…

