
Learn more about Canadian mortgage rates, rules and the latest news – read on!
Latest News


CMHC Makes Dividend Payments to Government: What are They and Who do They Help? + MORE Apr 5th
Starting in 2017, the Canada Mortgage and Housing Corporation (CMHC) has been making both special and regular dividend payments to its shareholder, the Government of Canada. The largest sum was for $4-billion in June 2017, which was spread over two years. At that time they announced the impl.... More »
Mortgage Professionals Canada promotes broker expertise in newly launched campaign + MORE Oct 17th
Mortgage Professionals Canada (MPC) has unveiled a new national campaign emphasizing the pivotal role mortgage brokers play in guiding Canadians towards their homeownership dreams..... More »
Tools to calculate your mortgage payments and costs in Canada Nov 1st
Owning real estate is a goal for many Canadians, and while it can be a rewarding investment, it comes with financial responsibilities that you must carefully manage. First and foremost, you need to be able to calculate your mortgage payments, down payment, penalty fees and other costs. Onli.... More »
Tips for Paying Off Credit Card Debt Jun 17th
Credit card bills got you down?
That’s the trouble with paying with plastic. It is easy to spend, but not quite as easy to pay off the debt you accrue – especially if you are only paying the minimum each month. Carrying too much credit card debt can make it harder to get a loan for a house .... More »
To hell with this home market + MORE Oct 13th
(Photo by Lucas Finlay)
Aaron Urion considers himself lucky. Very lucky. He has a great job as an associate at a downtown Vancouver architectural firm and, last summer, he married his sweetheart and sailing partner, Heather Thompson, 36. These days, the couple enjoy their evenings looking out over t.... More »
Report Finds CMHC Cracking Down on Foreign Investment in Canada
– ratesupermarket.ca

Frustrated would-be Canadian home buyers, priced out of their desired neighbourhoods, have long pointed to the invisible force of foreign investment as the impetus behind skyrocketing prices. Now, the Canada Mortgage and Housing Corporation (CMHC) is revealed to be taking a closer look, reports Bloomberg News. Via a freedom of information request, the news outlet has learned the CMHC has been in contact with at least eight government agencies to find data on offshore buyers in cities with the hottest real estate markets, including Toronto, Vancouver and Montreal. But will these efforts reveal an accurate assessment of the situation?
Related Read: Foreign Real Estate Investment – Will the Government Take Action?>
Why the Sudden Focus?
Canada’s housing market has been soaring for a better part of the last decade – even during the 2008 financial crisis, when American real estate experienced a meltdown. Throughout it all, Canadian market prices persevered. But now, as the average cost in Vancouver and Toronto tops the million mark, there are calls to understand where the money is coming from…
6 worst cities to buy an income property
– moneysense.ca
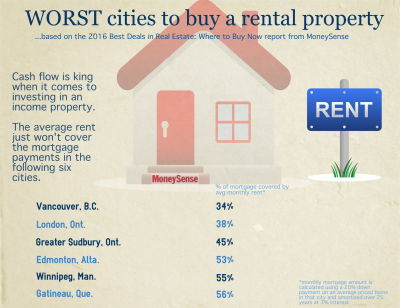 Buy a rental property in one of these six cities and you’ll struggle to get enough rent to cover your monthly mortgage payments, never mind all the other costs associated with rental properties. (Based on the analysis from 2016 Best Deals in Real Estate: Where to buy now report that was just released.)
And if you missed it, here are the six best cities to buy a rental property in.
Read more from Romana King at Home Owner on Facebook »
The post 6 worst cities to buy an income property appeared first on MoneySense.
Should you ever use an RRSP to pay tuition fees?
– moneysense.ca
 Q: I am a 55-year old with three kids who are in university. I have exhausted our RESP savings and am having a cash flow problem. My wife and I have about $250,000 in RRSPs and another $150,000 in LIRAs. We have had some money difficulties over the last couple of years and now have a $450,000 mortgage on a home that is worth around $650,000.
I am a good earner and make close to $200,000 before taxes. I am a psychologist in private practice. My wife works for me and we income-split to help reduce taxes.
The dilemma we are facing is whether or not we should sell our house and downsize into something a little cheaper in order to reduce our mortgage, or use some of the money that we have in RRSPs to pay down the mortgage and help with the kids’ education. Once they are done, we will have a lot more money to put against the mortgage, but what is killing us is the interest on the mortgage.
We are also thinking about building a house and have found a nice lot. We could probably do it for about $500,000…
One on One — With Gerald Soloway
– canadianmortgagetrends.com
If you look at all the people still in the mortgage business, few have changed the lending landscape like Gerald Soloway. A former lawyer, Mr. Soloway built a small savings and loan company with 12 employees into Canada’s largest alternative lender with 700+ employees. In the process, he created over $2 billion of shareholder value. Gerry was a trailblazer in lending to self-employed borrowers and those with meagre credit histories. His Home Capital Group is a testament to the successes possible in non-prime lending. We were thankful to have a few minutes of Gerry’s time last week for some Q&A. He shared thoughts on industry regulation, READ MORE
The Canadian Debt-to-Income Ratio Hits 165%
– ratesupermarket.ca
The latest household debt stats have been released by Statistics Canada – and they reveal a trend of persistent consumer and mortgage borrowing across the nation. The average debt-to-income ratio hit 165 per cent in the fourth quarter of 2015, up from 164 per cent in the previous quarter. That means the average Canadian now owes $1.65 for every dollar they earn after taxes.
Total debt, including consumer credit and non-mortgage and mortgage-based loans, grew 1.2 per cent to $1.923 trillion at the end of last year – but a whopping 1.262 trillion of that can be attributed to mortgages.
This follows a report from TransUnion that finds the average Canadian credit card balance has hit $3,610 – a three-year high.
Cheap Borrowing to Blame
It’s not surprising debt – and particularly mortgage borrowing – continues to grow in Canada; consumers have been spurred to borrow by the central bank for several years, as record low interest rates have been the norm. The Bank of Canada (BoC) cut the cost of borrowing to 0…

