
All about Retirement Planning in Canada. Learn the ins and outs and get the latest news.
Latest News


Suze Orman on why you should work until you’re 70, be careful giving money to your kids and sell your home sooner rather than later Mar 9th
Superstar personal finance guru Suze Orman, a frequent guest on the Oprah Winfrey Show, has some retirement advice just for Canadians.... More »
Ontario loosening solvency requirements for defined benefit pensions + MORE May 20th
Ontario is changing rules on workplace defined benefit pensions, including considering them to be solvent when they are 85 per cent funded.
The provincial Liberal government announced today that it would introduce legislation in the fall to make that change and others that it says will help keep def.... More »
How much should you withdraw from your RRIF? + MORE Aug 17th
Q. I am 78 and have $330,000 in my RRIF account. How much should I withdraw each year so it is depleted by age 90? –Sandy
A. If I understand your question, Sandy, it sounds like you want to draw down your registered retirement income fund (RRIF) on a schedule aligned with your life expectancy. .... More »
Why young people shouldn’t worry about retirement saving: Mayers + MORE Dec 18th
Logically, we should save for retirement first, then buy and pay off a house, and nearing retirement have children. Life doesn’t work like that..... More »
CPP Fund grows to $366.6B at end of June Aug 11th
Canada Pension Plan Investment Board says its main fund grew to $366.6 billion of net assets at the end of June, up $10.5 billion from the end of March..... More »
Boomers happy working longer, retiring later
– thestar.com
 Most Baby Boomers intend to work after retirement age or never retire at all. But some are making backup plans just in case.
Unwrap portfolio with index mutual funds
– moneysense.ca
 Photograph by Jenna Marie Wakani
The problem
With a paid-for home and six-figure portfolio, the couple’s friends think they have little to worry about. But “I do worry,” says Denise, who at 53 makes a good income as a dental hygienist. However, she enjoys no major benefits or employer-sponsored pension plan. Neither does Mark, 55, who lost his job in April 2011 and has worked only in contract positions since. They were investing $1,200 a month in RRSPs but ceased adding to Mark’s portion in November. The bank “wrap” program they’re invested in charges 2.5%. They’d prefer the lower fees of a “Couch Potato” but “don’t know how to do it ourselves.”
Financial planner Tony de Thomasis, of De Thomas Financial Corp., says the couple are moderate-risk investors and should be comfortable with an asset allocation of 75% equities to 25% bonds and cash. As retirement approaches and if markets cooperate, portfolios would be gradually rebalanced to raise the fixed-income weight by 8% every five years or so…
Retirement spending: You may need less than you think
– moneysense.ca
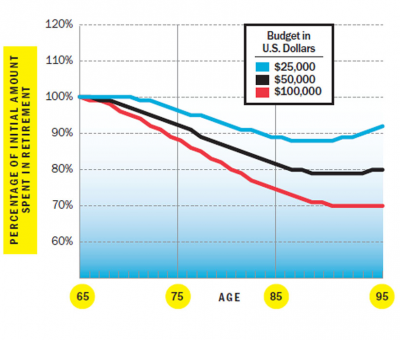 David Blanchett, head of retirement research at Morningstar Investment Management, ran the numbers on the actual spending patterns of retired couples over 30 years. He tracked three annual spending levels: US $25,000, $50,000 and $100,000. He found that as couples aged, they withdrew less than anticipated, mainly because they had simpler lifestyles. As a result, many retirees may need 10% to 30% less in savings than planners suggest.
Source: Morningstar Investment Management
The post Retirement spending: You may need less than you think appeared first on MoneySense.
 You can withdraw money tax-free from your RRSP when buying a home. But you must tell the bank why you’re doing it or face unwanted taxes.
What if You Have Different Retirement Planning Goals?
– rhondasherwood.com
If you are on your second marriage or married late in life, keeping your finances separate seemed like the sensible thing to do. The basic costs, such as the mortgage, utilities, taxes and insurance were split 50/50. You took care of your own personal needs and lifestyle costs. You have your own savings and retirement accounts.
This seems to be working perfectly fine and you assume it will continue on even into retirement. You have your pension from your many years of service that will cover your entire half of the basic costs. You have also aggressively saved over the years. When the mortgage was paid off, your portion of the payments was redirected right into your RRSP. You did everything right with the help of the road map created several years ago with your financial advisor. Retirement planning has never been a worry for you because you took charge and looked after it.
However, it dawns on you one day that you and hubby have never actually discussed retirement and what possibilities lay ahead for you both…

