
Retirement planning getting you down? There are always smart ways to plan the financial aspects of your retirement.
Latest News

The Future of Blackwater and Other Guns for Hire + MORE Oct 23rd
Paying for a soldier’s health care and retirement pension is far more costly than hiring contractors, even at exorbitant rates..... More »
Ontario loosening solvency requirements for defined benefit pensions + MORE May 20th
Ontario is changing rules on workplace defined benefit pensions, including considering them to be solvent when they are 85 per cent funded.
The provincial Liberal government announced today that it would introduce legislation in the fall to make that change and others that it says will help keep def.... More »
How to retire at 55 on $55,000 a year + MORE Jan 7th
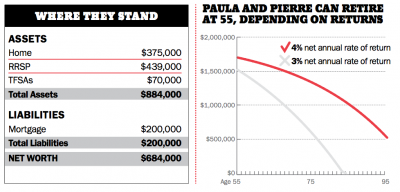
Paula Lorimer and husband Pierre Sopel save $30,000 annually. They hope to retire at age 55 with a net annual income of $55,000.
The current situation
Paula Lorimer, 40, is a psychologist living in Montreal. Right now, Paula is self-employed but is looking forward to changing gears at age 55. “Iâ€.... More »
What to expect when receiving OAS at 65 + MORE Jun 10th
(Shutterstock)
Right after tax season I received in the mail one of those little brown envelopes from the federal government. No, they weren’t after me for more tax money but the opposite: it was from Service Canada and they were proposing to send ME money as of my next birthday. The letter inform.... More »
In the years leading up to retirement, an updated financial plan is key: Experts + MORE Jun 29th
Retirement planning getting you down? There are always smart ways to plan the financial aspects of your retirement.
In the years leading up to retirement, an updated financial plan is key: Experts - thestar.comContinue Reading On thestar.com »
How to become a digital nomad—and not g.... More »
Despite pledge not to, Cianci has taken campaign cash from dozens of Providence city employees
– canadianbusiness.com
PROVIDENCE, R.I. – Ex-Mayor Buddy Cianci accepted campaign contributions from dozens of city employees in his comeback bid for City Hall despite saying he hadn’t and pledging he wouldn’t, according to campaign finance reports.
At a Sept. 17 mayoral forum, the 73-year-old independent addressed criticism about corruption and pay-to-play practices during his previous administrations.
“I haven’t taken a dime from any city worker, nor do I intend to,” Cianci said during the forum at the Laurelmead retirement community.
But campaign finance records filed Tuesday show that among those contributors who named their employers, more than five dozen city employees donated a total of about $18,000 to Cianci’s campaign. The reports cover the period from June 25, when Cianci announced his mayoral bid, through Oct. 6.
Some of the employees contributed several times, while others contributed once. Their donations ranged from $50 to $1,000, the maximum amount. Dozens of donations were made before Cianci made the comment Sept…
At a Sept. 17 mayoral forum, the 73-year-old independent addressed criticism about corruption and pay-to-play practices during his previous administrations.
“I haven’t taken a dime from any city worker, nor do I intend to,” Cianci said during the forum at the Laurelmead retirement community.
But campaign finance records filed Tuesday show that among those contributors who named their employers, more than five dozen city employees donated a total of about $18,000 to Cianci’s campaign. The reports cover the period from June 25, when Cianci announced his mayoral bid, through Oct. 6.
Some of the employees contributed several times, while others contributed once. Their donations ranged from $50 to $1,000, the maximum amount. Dozens of donations were made before Cianci made the comment Sept…
You Can Retire on Less Money (and Make it Work for You)
– rhondasherwood.com
Saving for financial goals, including retirement, is a challenge for most people these days. Retirement is often left on the back burner until later in life when it may be too late to save the full amount you think you need. Rather than putting off your retirement or continuing to work, consider downsizing your lifestyle and overall expenses so that you can retire on less money.
Figure Out How to Downsize your Life
While you may love your house, do you need to continue living in a large home? Once your children are gone and you and possibly your spouse are left, it probably doesn’t make sense to maintain a big house. It could be less expensive to move into a smaller home where you will be paying less for utilities, property taxes and insurance. If you are in strata you also won’t have to worry about gardening or lawn maintenance, leaving you with fewer headaches to deal with. Downsizing may also leave you with more money from the sale/repurchase of your home to fund your retirement needs…
Investing outside RRSPs and TFSAs
– moneysense.ca
 Getty Images
Q: After I max out my RRSP and TFSA contributions, what can I invest in?—Dale
A: Congratulations on maxing out your RRSP and TFSA, Dale. Statistics show that there’s a lot of unused RRSP and TFSA room in Canada, so maxing yours out is no small feat.
Depending on your situation, there are a few other options you should consider for your savings.
Are you debt-free? If not, I’d consider paying down your remaining debt (including the mortgage) before investing. Debt repayment is an investment with a guaranteed return and that return will rise as interest rates increase. Plus your non-registered investment income is taxable, meaning you keep less of your returns compared to those in your RRSP and TFSA.
Do you have kids? Consider maxing out their RESPs to help save for their post-secondary education costs. Depending on your financial situation, if they’re over the age of 18, you might even consider making contributions to their TFSA accounts. Just remember, that money becomes their money…
Lower long-term interest rates and updated actuarial tables that project longer life spans for Canadian retirees, are expected to put a squeeze on Canadian pension plans
5 rules to pay less tax
– moneysense.ca
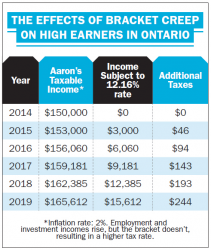 Do you plan to be wealthy? Then it’s time to go to tax school. As your kids head back to the classroom to learn to read and write, you can learn basic taxation principles that will help you build wealth faster.
There’s a reason why those who have more, care more about taxes. They know that what’s truly important is your “real net worth”—the net value of assets after taxes, inflation and accumulation costs such as interest on debt and professional fees. It’s all about what you keep and what it’s worth when you need it. Learn these five important tax principles, and you’ll have a more enlightened view of what wealth is, and how to build it faster.
1. Understand what income is. Make it your business to understand tax jargon. Start by learning the definitions of income: total income, net income, taxable income, earned income for RRSP purposes—they all have different meanings. The most important of these is “net income,” because that’s the figure used in many federal and provincial tax credit calculations…

