
Maximizing spousal RRSP contributions in your 70s + MORE Mar 23rd

Is it best to own a first home as an income property or primary residence? + MORE Jun 1st
Should you loan money to someone who is house rich and cash poor? May 18th

The one thing influencers Steph & Den want you to know about retirement + MORE Apr 26th
What time of year should you retire? Sep 7th
Using your TFSA as a learning tool
– moneysense.ca
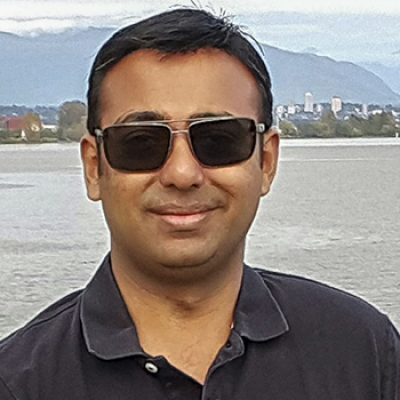
Raj Thirumeni
AGE: 28
PLACE: Vancouver
TFSA TOTAL: $17,000
STRATEGY: Stocks
Me and my TFSA
Raj Thirumeni is 28-years-old and works for the banking operations of a large financial institution. He has several degrees, including a Master of Science in project management, an MBA, as well as a mechanical engineering undergraduate degree from the University of Windsor. After all those years of study, he now has a full-time job but since he isn’t earning enough yet to make contributing to an RRSP feasible, he’s decided to concentrate on beefing up his investing through his TFSA.
Raj opened his TFSA in 2015 with a $5,500 contribution. “I learned about it from my TD Bank branch,” says Raj. “I was applying for a credit card and the teller told me about it and explained the basics to me.”
TFSA contribution room calculator »
Before making his first investment, Raj spent a few months watching the oil and gas markets. As oil prices were falling in 2016 he bought his first stock: TransCanada Pipeline…
Retirees should be happy not to qualify for GIS
– moneysense.ca
 (Izabela Habur/Getty Images)
Canada’s chief actuary has released a report that says the enhanced Canada Pension Plan could eventually “disqualify” 243,000 low-income seniors from receiving the Guaranteed Income Supplement (GIS). No doubt this makes for compelling media headlines but really, so what?
If your employer suddenly offered you a gold-plated inflation-indexed pension plan, you’d welcome it even if it meant you would no longer qualify for the GIS, which is a supplement to Old Age Security and goes to only the poorest third of OAS recipients after the qualifying age of 65.
GIS benefits are “means-tested” and tax-free, but single seniors who earn more than $17,688 a year won’t qualify for them. Currently, maximum CPP benefits taken at the normal retirement age of 65 max out at $13,110 per person, but the enhanced CPP would eventually raise this to $20,000, which is above the GIS threshold. Keep in mind that even as things stand, CPP benefits can be increased 42% by waiting till age 70 to start receipt of benefits…

Q. I was surprised to find out from a friend that making an in-kind transfer of losing stocks from a non-registered account to a TFSA would not trigger a “deemed disposition” for tax purposes. However, if the stocks had gone up in value, there would be a deemed disposition and you would have to pay the tax on any capital gains. That doesn’t make any sense to me. Can you confirm this policy and provide some explanation? — Rudy B.
A. Your friend is correct, Rudy. If you hold stocks showing a loss in a non-registered account and you transfer them in kind to your TFSA (or your RRSP, for that matter), you cannot claim a capital loss. However, if you transfer stocks with unrealized gains, then Canada Revenue Agency considers this a “deemed disposition,” and you would be responsible for reporting the capital gains and paying tax on them.
This sounds unfair, but it’s really not. To understand why we need to review the CRA’s treatment of capital gains and losses.
Normally, when you sell an investment for less than you paid, you can claim a capital loss, which you can use to offset capital gains you have realized in the current year or up to three years in the past…
 If you don’t know if you’re on track for retirement, who does?

