
There are plenty of bank savings account options in Canada! Stay on top of the best plans right here.
Latest News




Can you put an inheritance into a joint account? + MORE Jul 1st
An inheritance can raise questions about taxes, family law, and how to manage the money. This article focuses on the income tax considerations for married and common-law couples who invest inherited funds.
Taxation of an inheritance
First off, the receipt of an inheritance is generally not tax.... More »
This 29-year-old has been laid off twice as a server and is starting from scratch, spending all his savings to study UX design. Living at home, he wants financial help + MORE Mar 20th
Peter, 29, a server working in Halton Region, was laid off for the second time in December, during COVID-19’s second wave. Currently, he’s receiving $1,800 a month (before tax) through Employment Insurance..... More »
Your March Money Update + MORE Mar 10th
March may come in like a lion, but our economy is in for a lambish season. The Bank of Canada has decided to hunker down and wait out the short-term effects of oil, declaring last month’s interest-rate cut will be enough to keep spending and inflation afloat.
Meanwhile, a debate rages over Canadi.... More »
Household debt climbs to 167% of disposable income + MORE Dec 16th
(JGI/Jamie Grill)
TORONTO – Canadian household debt hit a record high during the third quarter, as it grew at a faster pace than disposable income, according to the latest figures from Statistics Canada.
The total amount of credit market debt — which includes mortgages, non-mortgage loans an.... More »
“How can I lower my auto insurance bill during COVID-19 lockdown?” + MORE May 2nd
On April 8, 2020, the Insurance Bureau of Canada released the following statement:
To help Canadians cope with the financial impact of COVID-19, the Insurance Bureau of Canada (IBC) member companies are offering substantial consumer relief measures. For consumers whose driving habits have changed si.... More »
Are Kids of Immigrants Financially Savvier?
– ratesupermarket.ca
Are the children of immigrants financially savvier than those born in Canada? Pracheer Saran explores the phenomenon of greater financial literacy among newcomers – and what everyone can learn from frugal living practices.
One aspect of starting a life in Canada that has always baffled me is the ability of immigrant children, as young as eight or nine years old, to be quite financially responsible, especially compared to kids who were born in Canada. Now, I’m not being judgemental here – I have concrete reason to support this claim.
Learning From Example
Consider this – the majority of immigrants to Canada come without a job offer in hand. They look for employment once they have relocated here, and survive on savings or low-paying work while they hunt for jobs in their field. Such situations require excellent financial planning skills, especially when one has immigrated with kids. And, as almost all conversation among immigrants revolves around ways to save money, kids are exposed to such financial issues and practices from an early age…
Canadians spending more on taxes than on necessities
– moneysense.ca
VANCOUVER – A new study says the average Canadian family was spending more on taxes than on food, shelter and clothing combined.
The Fraser Institute study says that in 2013, the average Canadian family earned $77,381 and paid $32,369 in total taxes, or 41.8 per cent of income, compared with 36.1 per cent for food, shelter and clothing combined.
By comparison, in 1961 the average family earned about $5,000 and spent 56.5 per cent of its income on food, shelter and clothing, while $1,675 went to taxes (33.5 per cent).
The study says the total tax bill represents both visible and hidden taxes paid to the federal, provincial and local governments. This includes income taxes, payroll taxes, health taxes, sales taxes, property taxes, fuel taxes, vehicle taxes, import taxes, alcohol and tobacco taxes.
The think tank says that since 1961, the average Canadian family’s total tax bill has increased by 1,832 per cent, moving past increases in shelter costs (1,375 per cent), clothing (620 per cent) and food (546 per cent)…
The Fraser Institute study says that in 2013, the average Canadian family earned $77,381 and paid $32,369 in total taxes, or 41.8 per cent of income, compared with 36.1 per cent for food, shelter and clothing combined.
By comparison, in 1961 the average family earned about $5,000 and spent 56.5 per cent of its income on food, shelter and clothing, while $1,675 went to taxes (33.5 per cent).
The study says the total tax bill represents both visible and hidden taxes paid to the federal, provincial and local governments. This includes income taxes, payroll taxes, health taxes, sales taxes, property taxes, fuel taxes, vehicle taxes, import taxes, alcohol and tobacco taxes.
The think tank says that since 1961, the average Canadian family’s total tax bill has increased by 1,832 per cent, moving past increases in shelter costs (1,375 per cent), clothing (620 per cent) and food (546 per cent)…
Did You Over-Contribute to Your TFSA? You’re Not Alone
– ratesupermarket.ca
The Tax Free Savings Account (TFSA) has now been available to Canadian consumers for six years – but Canadians are still unclear on how to use it.
The TFSA is a registered savings vehicle that allows money inside it to grow tax-free. This is unlike the Registered Retirement Savings Plan (RRSP), where tax must be paid upon withdrawal. Within set guidelines, the TFSA allows Canadians to easily withdraw and deposit money. However, it’s these guidelines that still trip up banking customers – and they’re paying fees for their mistakes.
Understanding Your TFSA
The TFSA allows Canadians, age 18 and over, to set money aside tax-free throughout their lifetime. Each calendar year, you can contribute up to the TFSA dollar limit for the year (the annual contribution limit in 2014 is $5500), plus any unused TFSA contribution room from the previous year, and the amount you withdrew the year before. However, the biggest mistake made by Canadians is maxing out their annual contribution room, withdrawing their funds, and then attempting to restore them within the same calendar year – a big tax no-no…
How to manage multiple investment accounts
– moneysense.ca
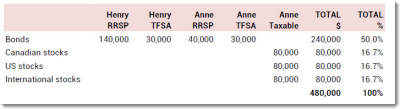 Model portfolios like those I recommend are ideal for investors who have a single RRSP account. But life isn’t so simple once you’ve accumulated a significant portfolio: chances are you’ll be managing two or three accounts, and if you have a spouse there may well be a few more.
In most cases, it’s most efficient to consider both partners’ retirement accounts as a single large portfolio. In other words, there’s no my money and my spouse’s money: there’s only our money. This strategy has a couple of advantages: first, it allows the family to make the most tax-efficient asset location decisions. Second, it keeps the overall number of holdings to a minimum, which reduces transaction costs and complexity.
Meet Henry and Anne, who have a combined portfolio of $480,000. Let’s assume they are the same age and plan to retire at about the same time. Their financial plan revealed that a mix of 50% bonds and 50% stocks is suitable for their risk tolerance and goals. Anne has a generous defined-benefit pension plan and therefore has little RRSP room: most of her personal savings go to a non-registered account…
Students anticipate huge debt will disappear fast
– moneysense.ca
TORONTO – Getting a post-secondary degree can be an expensive endeavour, but a recent survey suggests that most students believe they’ll be on track to pay off their student loans within five years of graduating.
The poll from CIBC (TSX:CM) found that about half, or 51 per cent, of post-secondary students said they would need to borrow money to pay for tuition, living expenses and books.
Although about a quarter expected to owe less than $10,000 by the time they graduate, almost three quarters (73 per cent) expected to owe more than $10,000, including 40 per cent who said they’d likely be on the hook for $25,000 or more of student debt.
The Canadian Federation of Students says students in Ontario and the Maritimes have debt loAds averaging $28,000 at graduation, the highest in the country.
Yet despite the predictions of big debt, most students remain optimistic about their ability to eliminate it.
Sixty-six per cent surveyed believed they’d be able to pay down their debt within five years or less, while 34 per cent expected it would take them more than six years to be debt-free…
The poll from CIBC (TSX:CM) found that about half, or 51 per cent, of post-secondary students said they would need to borrow money to pay for tuition, living expenses and books.
Although about a quarter expected to owe less than $10,000 by the time they graduate, almost three quarters (73 per cent) expected to owe more than $10,000, including 40 per cent who said they’d likely be on the hook for $25,000 or more of student debt.
The Canadian Federation of Students says students in Ontario and the Maritimes have debt loAds averaging $28,000 at graduation, the highest in the country.
Yet despite the predictions of big debt, most students remain optimistic about their ability to eliminate it.
Sixty-six per cent surveyed believed they’d be able to pay down their debt within five years or less, while 34 per cent expected it would take them more than six years to be debt-free…

