
Personal Savings getting you down? There are always smart ways to increase your savings.
Latest News


Canada’s 10 best Mastercard credit cards for 2021 + MORE May 16th
As one of the top credit card companies in the world, Mastercard is extremely popular and also widely accepted. For those already banking at BMO Bank of Montreal, a major Canadian bank that’s associated with Mastercard, these cards may offer all the perks you’re after, along with opportunities t.... More »
3 Reasons Why You Need to Contribute to Your RRSP… Now Jan 25th
Why is everyone always rushing to contribute to RRSPs this time of year? And does it makes financial sense for you to make extra contributions before the March 1 deadline?
This time of year is often referred to as RRSP season, as many of us rush to make contributions before the RRSP contribution.... More »
What types of tax-free savings accounts (TFSAs) exist? + MORE Jun 19th
A tax-free savings account (TFSA) is a fantastic way to earn money on your savings, without having to pay tax on those earnings. Registered by the federal government, TFSAs are available to Canadians aged 18 and older. Unlike a registered retirement savings plan (RRSP), you cannot deduct contributio.... More »
2023 tax credits, due dates and when you can file: Your 2023 income tax return guide + MORE Mar 19th
You’ll want to bookmark the MoneySense guide for 2023 personal income taxes. We will be updating it frequently, as information becomes available and deadlines approach. Plus, we get answers from the experts you won’t find anywhere else, thanks to our Ask MoneySense and Ask A Planner columns.&nbs.... More »
Gas Prices Are High. Would a Federal Tax Break Make a Difference at the Pump? Jul 3rd
With U.S. president Joe Biden calling on Congress to pause federal taxes on gas and diesel for three months to help Americans, some Canadians are wondering if a similar initiative may offer a temporary reprieve from high prices north of the border.
As of May, gas prices in Canada are up 48 .... More »
How to get the pension income tax credit
– moneysense.ca

Q: I am 65 years old and will have income for the next three years. I want to open a Registered Retirement Income Fund (RRIF) and transfer some money into it to take advantage of the pension credit on a $2,000 withdrawal. While doing so, can I then turn around and use that $2,000 as part of my contribution to my RRSP? In other words, can you withdraw from an RRIF and contribute to your RRSP in the same year?
—Rhonda P.
A: Thank you, Rhonda, for your question. I assume that you do not have a pension—and you didn’t mention the value of your RRSPs. For many, it’s a great strategy to open an RRIF and transfer net $2,000 from your RRSP in order to take advantage of the pension credit. Be sure to transfer a little bit extra to the RRIF so the $2,000 withdrawal does not deplete the RRIF and cause it to close. Your financial institution will advise you on what the minimum amount is to keep the RRIF open. Or you can transfer as a lump sum.
And yes—you can technically withdraw from an RRIF and then contribute to an RRSP—if you have the room and are still under 71 years of age…
How to start investing late in life
– moneysense.ca
 Flickr
Q: I am a late bloomer. I finally have an empty nest, but I had low income employment and always lived with my nose 1 inch under the water. I finally have a good paying job at a bank, minimal debt, and I want to save. I have no idea where to go. My bank opened an investment account and I can finally put money into it this month. Please help.
—Pamela
A: Don’t feel bad about being a late bloomer, Pamela. Life happens, and we do our best. And don’t feel bad about needing help with your investment strategy. They don’t teach you this stuff in school and I frequently meet intelligent, successful people who don’t know the first thing about personal finance or investing.
First things first, you should figure out what kind of investment account the bank opened for you. Given you work at a bank, I’m wondering if this is some sort of account related to your employment? Often employers will offer defined contribution (DC) pension plans or group registered retirement savings plans (RRSPs) with matching contributions made by the company…
RRSP vs TFSA: Where to store your retirement savings
– moneysense.ca
 —In partnership with Scotiabank—
The post RRSP vs TFSA: Where to store your retirement savings appeared first on MoneySense.
A guide to having retirement income for life
– moneysense.ca
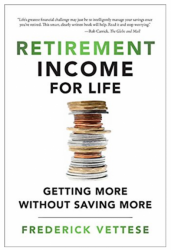 With 1,100 Canadians reaching the official retirement age of 65 every day, there’s a sea of change occurring in the investment world. The move from wealth accumulation is rapidly moving to its opposite, de-accumulation or “decumulation.”
Decumulation is actuary Fred Vettese’s preferred term over “drawdown” and his new book Retirement Income for Life (Milner & Associates, Toronto, 2018) seems destined to become the bible of any new or near retiree challenged with converting large RRSPs and other savings into reliable income.
The only retirees who may not need this book are the fortunate few and increasingly rare members of traditional Defined Benefit (DB) pensions. As Vettese says – the chief actuary for Morneau Shepell Inc. – decumulation is a much trickier act than accumulation. The book covers some ground previously occupied by Moshe Milevsky’s Pensionize Your Nest Egg or Daryl Diamond’s Retirement Income Blueprint but Vettese takes the topic further.
What I like about Vettese’s book is a 5-part strategy involving what he terms “enhancements…

