
Canada has several major banks and many schedule II banks – but with rates and plans all over the map, it’s difficult to know where to bring your business. Our aim is to help you navigate Canada’s banking options to discover which one suits your needs best.
Latest News

GICs have a hidden commission Mar 31st
Shutterstock
Q. After buying two GICs, I received a statement showing $575 in commissions paid to my broker by a third party. I thought GICs were free of commissions. Any light you could shed on these fees would be greatly appreciated.
— Tom
A. There are few universal truths in investing, Tom, but.... More »
How to cut costs on international money transfers Jan 10th
While many Canadians know how expensive it can be to send money abroad, they’re likely unaware of how the costs are broken out. But one virtual bank is changing that.
EQ Bank has formed a partnership with TransferWise, a global money transfer platform that’s committed to being cheap, fast and tr.... More »
Best FHSAs in Canada: What to know about the new first home savings account Mar 29th
First home savings account (FHSA) highlights
The FHSA is a type of registered account that allows you to contribute up to $8,000 annually, up to a lifetime limit of $40,000, to save for the purchase of your first home.FHSAs are scheduled to become available as early as April 1, 2023. However, availa.... More »
U.S. targets Putin's daughters with sanctions amid outrage over civilian deaths in Ukraine - CBC News + MORE Apr 6th
U.S. targets Putin's daughters with sanctions amid outrage over civilian deaths in Ukraine CBC NewsRussia-Ukraine live updates: U.S., U.K. unveil new sanctions in bid to escalate Russian financial shock The Globe and MailUkraine news: Sanctions for Putin's daughters, Russian ba.... More »
Financial Institution Numbers for All Canadian Banks Apr 1st
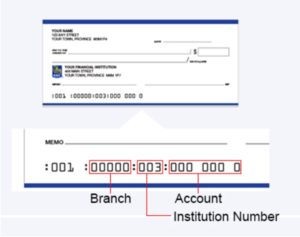
You can identify Canadian financial institutions by their bank institution number, which is always three digits long. Bank customers need this number anytime they want to set up a direct deposit or preauthorized payment or receive a wire transfer into their account.
How to Locate Canadian Bank Insti.... More »
U.S. tax overhaul a present for big Canadian banks
– theglobeandmail.com
The sweeping tax cuts are expected to boost earnings per share at four of Canada’s largest lenders by 1 per cent to 3 per cent
Personal Loan Vs. Line of Credit: Which Should I Get?
– ratesupermarket.ca
In today’s ever-evolving market of loan products, it can sometimes feel like there are too many options to choose from – and each with its own complex fine print. Obtaining a line of credit or personal loan from a bank or lender has been a common way for Canadian consumers to get a cash injection for decades.
But what are the differences between the two? And when may someone be advised to apply for a personal loan over a line of credit, or vice versa?
Why should I get a line of credit?
A line of credit has many similar features to that of a credit card, allowing the consumer to borrow money up to a pre-set limit. The borrower can use the funds however they choose and can spend as little or as much of the allotted credit. Most lines of credit also offer interest-only payment agreements, allowing the borrower to pay back the principal balance at any time.
Personal lines of credit may be secured or unsecured, but borrowers are advised to apply for secured lines of credit when possible…

