
The “Big Five” Canadian banks include Royal Bank of Canada, Toronto Dominion Bank (TD Canada Trust), Bank of Nova Scotia, Bank of Montreal and Canadian Imperial Bank of Commerce (CIBC). Are there other viable options?
Latest News

The best high-interest savings accounts in Canada for 2023 Oct 20th
Save
The best high-interest savings accounts in Canada for 2023
Here are the accounts offering the highest interest rates and lowest fees.
Compare now
Tap the button for more details.
The rates i.... More »
Banks and other industries embrace biometrics to boost security, convenience Jul 22nd
TORONTO – In the not-too-distant future, your bank will be able to prevent fraud by learning how you type, your car will unlock when it senses the electrical activity of your heart and the security system at your office will recognize your facial features.
That’s according to experts in .... More »
The best 5-year fixed mortgage rates in Canada Mar 22nd
Mortgage rate comparison tool
Customize the filters to compare rate types and terms.
powered by
Why trust us
MoneySense is an award-winning magazine, helping Canadians navigate money matters since 1999. Our editorial team of trained journalists works closely with leading personal finance .... More »
The Best Gas Rewards Credit Cards of 2019 Dec 11th
Let’s say your biggest monthly expense is gas; it’s a reality for a lot of people who maybe travel a lot for work or have a long daily commute. Or maybe you and the family go on a lot of road trips, or you just like long drives down country roads to “get away from it all.” No matter the cas.... More »
The best GIC rates in Canada for 2024 Oct 16th
GIC comparison tool
Find the best and most up-to-date GIC rates in Canada using the comparison tool below. Plus, use the filters to assess your estimated rate of return based on the size of your balance.
Why trust us
MoneySense is an award-winning magazine, helping Canadians navigat.... More »
3 Mortgage Marketing Tactics You Should Be Aware Of
– ratesupermarket.ca
Spring is always a competitive season for mortgage lenders, but this year is a true standout; lenders small and large (including the Bank of Canada) have cut rates, some to historic lows – five-year fixed options have dipped as low as 2.44 per cent in some provinces, and even Canada’s big banks are offering rates below the 3 per cent threshold.
In fact, things have gotten so hot, that lenders are getting creative with their discounts; not content to simply offer the lowest rate, we’ve seen a few tactics this year that put a new spin on mortgage marketing. Here’s a look at what’s been introduced in the market so far.
Click here to see the best mortgage rates in your region>
Big Banks Getting in on the Game
Usually it’s brokers and other smaller lenders who push the pricing envelope – but in March, BMO and TD made headlines by cutting their 5-year fixed rates to 2.79 per cent – the lowest ever for large federally-regulated banks (TD has since cut further to 2…
NDP seeks ban on so-called ‘pay-to-pay’ fees at banks
– macleans.ca
OTTAWA – The NDP has called on Ottawa to ban so-called “pay-to-pay” fees charged by Canada’s big banks.
NDP MP Andrew Cash said Thursday that he wants an expanded code of conduct for the banks that is not voluntary.
“Offering the banks a voluntary code of conduct is like telling a cat to regulate its consumption of cat nip,” the NDP critic for consumer protection said.
Ottawa moved to block telecommunication and cable companies from charging fees for paper bills last year.
However, Cash said the banks were excluded from the legislation.
“You shouldn’t have to pay money to pay your bill; you shouldn’t have to pay money to pay your mortgage; you shouldn’t have to pay money to pay your student loan,” he said.
Finance Minister Joe Oliver said the government has taken action to improve access to low-cost and no-cost banking options.
“Our government believes with better information Canadian consumers can make informed choices which will be in their interest,” Oliver said in response to a question by Cash in the House of Commons…
NDP MP Andrew Cash said Thursday that he wants an expanded code of conduct for the banks that is not voluntary.
“Offering the banks a voluntary code of conduct is like telling a cat to regulate its consumption of cat nip,” the NDP critic for consumer protection said.
Ottawa moved to block telecommunication and cable companies from charging fees for paper bills last year.
However, Cash said the banks were excluded from the legislation.
“You shouldn’t have to pay money to pay your bill; you shouldn’t have to pay money to pay your mortgage; you shouldn’t have to pay money to pay your student loan,” he said.
Finance Minister Joe Oliver said the government has taken action to improve access to low-cost and no-cost banking options.
“Our government believes with better information Canadian consumers can make informed choices which will be in their interest,” Oliver said in response to a question by Cash in the House of Commons…
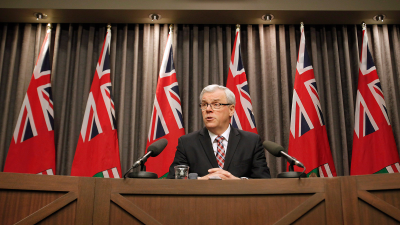 Manitoba Premier Greg Selinger. (The Canadian Press)
WINNIPEG – Smokers and banks will pay more to help pay for Manitoba’s spending on infrastructure in a deficit budget that borrows heavily from a dwindling rainy-day fund.
The governing NDP has tabled a $15-billion budget that boosts tobacco taxes by $1 a carton and increases the capital tax on financial institutions to six per cent from five per cent.
The budget — which includes a $422-million deficit — also increases tax credits for the caregivers of vulnerable relatives at home and boosts rental assistance for welfare recipients by up to $271 a household.
“We made a decision to invest in infrastructure. We made a decision to invest in health care. We made a decision to invest in education,” Finance Minister Greg Dewar said Thursday.
“Other provinces have taken a different route.”
The budget draws $105 million from Manitoba’s rainy-day fund to pay down debt and support infrastructure spending…
3 Mortgage Marketing Tactics You Should Be Aware Of
– ratesupermarket.ca
Spring is always a competitive season for mortgage lenders, but this year is a true standout; lenders small and large (including the Bank of Canada) have cut rates, some to historic lows – five-year fixed options have dipped as low as 2.44 per cent in some provinces, and even Canada’s big banks are offering rates below the 3 per cent threshold.
In fact, things have gotten so hot, that lenders are getting creative with their discounts; not content to simply offer the lowest rate, we’ve seen a few tactics this year that put a new spin on mortgage marketing. Here’s a look at what’s been introduced in the market so far.
Click here to see the best mortgage rates in your region>
Big Banks Getting in on the Game
Usually it’s brokers and other smaller lenders who push the pricing envelope – but in March, BMO and TD made headlines by cutting their 5-year fixed rates to 2.79 per cent – the lowest ever for large federally-regulated banks (TD has since cut further to 2…

