
Canada has several major banks and many schedule II banks – but with rates and plans all over the map, it’s difficult to know where to bring your business. Our aim is to help you navigate Canada’s banking options to discover which one suits your needs best.
Latest News
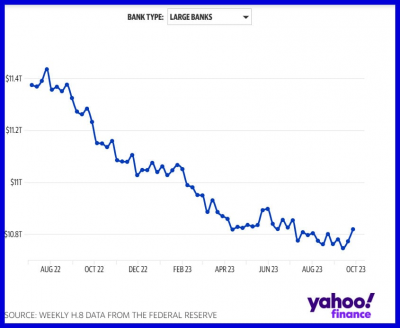
Making sense of the markets this week: October 22, 2023 Oct 21st
Kyle Prevost, creator of 4 Steps to a Worry-Free Retirement, Canada’s DIY retirement planning course, shares financial headlines and offers context for Canadian investors.
Big wins for big U.S. banks
If you’ve been betting against American consumers over the last few years, then you havenâ.... More »
What Negative Interest Rates Mean for Canadians Jun 1st
Even before COVID-19 began to dominate the collective consciousness, the possibility of negative interest rates garnered plenty of attention in the press. Just last year, in the midst of a U.S./China trade war, Donald Trump mused about the Federal Reserve heading into negative territory in order to .... More »
Canadians getting sick trying to cut food costs: study - CityNews Toronto + MORE Apr 27th
Canadians getting sick trying to cut food costs: study CityNews TorontoCanadian food banks are on the brink: ‘This is not a sustainable situation’ Global NewsCanadians are taking more risks with their food due to high prices National PostCHARLEBOIS: The hidden co.... More »
The best high-interest savings accounts in Canada for 2025 + MORE Aug 18th
Savings comparison tool
Find the best and most up-to-date savings rates in Canada using the comparison tool below. Plus, use the filters to assess your estimated return based on the size of your balance.
Advertisement
Why trust us
MoneySense is an.... More »
Advice for cash-strapped renters and landlords during COVID-19 May 16th
When the COVID-19 pandemic swept across North America in early 2020, it created a wave of income loss that impacted people from all walks of life. While some individuals have been hit harder than others, it’s difficult to find a group or industry that hasn’t been affected. A small segment of the.... More »
Canada’s biggest banks raised their prime interest rates one after another this week following the Bank of Canada increase of its policy rate to 0.75 per cent from 0.5 per cent. The base lending rate at the Big Six now is 2.95 per cent, compared with 2.7 percent before the central bank’s announcement on July 12.
That’s how it is supposed to work. Except, the “transmission mechanism” between central bank to private banks isn’t always so automatic. When the Bank of Canada cut interest rates in 2015, the banking oligopoly was less keen to reduce what it charges borrowers for money. Also: higher prime rates don’t necessarily result in significantly higher deposit rates.
The trend:
The financial crisis and its aftermath has been a public relations nightmare for banks. Their greed was seen by many as a major cause of the meltdown that brought on the Great Recession, and many of the worst actors got government bailouts. And then, as central banks dropped their benchmark interest rates to zero to prevent a depression, banks balked at passing on the full benefits of the cuts to their customers…
That’s how it is supposed to work. Except, the “transmission mechanism” between central bank to private banks isn’t always so automatic. When the Bank of Canada cut interest rates in 2015, the banking oligopoly was less keen to reduce what it charges borrowers for money. Also: higher prime rates don’t necessarily result in significantly higher deposit rates.
The trend:
The financial crisis and its aftermath has been a public relations nightmare for banks. Their greed was seen by many as a major cause of the meltdown that brought on the Great Recession, and many of the worst actors got government bailouts. And then, as central banks dropped their benchmark interest rates to zero to prevent a depression, banks balked at passing on the full benefits of the cuts to their customers…
 (iStock)
Canada’s biggest banks raised their prime interest rates one after another this week following the Bank of Canada increase of its policy rate to 0.75 per cent from 0.5 per cent. The base lending rate at the Big Six now is 2.95 per cent, compared with 2.7 per cent before the central bank’s announcement on July 12.
That’s how it is supposed to work. Except the “transmission mechanism” between the central bank and private banks isn’t always so automatic. When the Bank of Canada cut interest rates in 2015, the banking oligopoly was less keen to reduce what it charges borrowers for money. Also: higher prime rates don’t necessarily result in significantly higher deposit rates.
The trend:
The financial crisis and its aftermath has been a public relations nightmare for banks. Their greed was seen by many as a major cause of the meltdown that brought on the Great Recession, and many of the worst actors got government bailouts. And then, as central banks dropped their benchmark interest rates to zero to prevent a depression, banks balked at passing on the full benefits of the cuts to their customers…

