
Obtaining a mortgage or secured line of credit in Canada at the best rates is often a daunting task. We can help! Read the articles below for more info.
Latest News



Q4 2019 Bank Earnings – Mortgage Morsels + MORE Jan 11th
Profits were down among the big banks in what has been called a “bleak” fourth-quarter earnings season. It was the weakest earnings growth since 2016, particularly for the likes of TD and CIBC, who saw their net income fall 3% and 6%, respectively, compared to last year. TD President and.... More »
Making sense of the markets this week: September 24, 2023 + MORE Sep 23rd
Allan Small, Senior Investment Advisor at the Allan Small Financial Group with iA Private Wealth, shares financial headlines and offers context for Canadian investors.
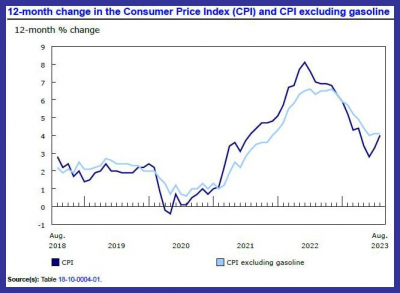
No surprise: Canada’s inflation rate ticked up in August
Canada’s annual inflation rate jumped to 4% in August, up from 3..... More »
Canada’s best credit cards for people with bad credit 2021 Jan 10th
Conventional wisdom may lead you to believe that if you have bad credit, you should swear off credit cards. But if you want to improve your credit score, you’ll have to show you can handle credit responsibly—and the only way to do that is (you guessed it) to have a credit card. When used properl.... More »
Trump Tower In Toronto Fails To Find Buyer Mar 7th
The sale of Toronto’s Trump Tower failed to attract a single bid from anyone except the lender that owns its debt, according to news reports.
Plagued by years of financial losses, the Trump International Hotel & Tower Toronto went into receivership last year, after defaulting on a C$260-milli.... More »
I need to lower my monthly mortgage payments. Is extending my amortization period a good idea? Nov 16th
An extra five years might not seem like much, but the difference can be startling, says one expert..... More »
New Federal Mortgage and Real Estate Rules Announced
– ratesupermarket.ca

You’d have to have been living under a rock – and certainly not in a house – to not know that various experts are concerned the Canadian real estate market is in the midst of bubble that will eventually pop, particularly in the super-hot Toronto and Vancouver markets. Earlier this month, the federal government announced some key financial changes that it hopes will help rein in ever-escalating house prices and help avoid a disastrous crash in the Canadian housing market. These changes are now in effect.
Sweat Equity
The first change is having mortgage lenders implement a so-called “stress test” to all applicants who apply for a mortgage with less than a 20 per cent down payment (i.e. high-ratio mortgages) to ensure they can still afford to make their payments if – and when – interest rates rise. The way they’ll do that is, no matter what rate you manage to negotiate with your lender, you’ll have to qualify for a mortgage based on the five-year conventional mortgage rate that the Bank of Canada posts every week…
How much you’d save if you skipped buying a house
– moneysense.ca
Before this, read “To Hell with this Home Market” to learn all about ways to have a home without buying a house in Canada’s crazy housing market.
Float home
COST SAVINGS: $200,000 cheaper than some Vancouver condos
WHO IT’S FOR: Home buyers who want a piece of Vancouver shoreline, but can’t stomach a million-dollar mortgage
WHO IT ISN’T FOR: People with mobility issues or who don’t like the idea of shovelling their roof
HOT TIP: If you don’t want to pump out your septic tank each month you can pay the marina about $10 to do it
Cottage escape
COST SAVINGS: Considerable, especially if you steer clear of vacation hotspots
WHO IT’S FOR: The self-employed
WHO IT ISN’T FOR: People who can’t stand the thought of weekend cottage traffic
HOT TIP: Older cottages are often sold “contents-in” which means that you may inherit old love letters from a bygone era or a crocheted wall plaque
Build an Earthship
COST SAVINGS: Huge. You can build for about $25 per square foot
WHO IT’S FOR: Hands-on builders and those who don’t mind lots of digging
WHO IT ISN’T FOR: Anyone who hates the idea of living in Yoda’s Dagobah home
HOT TIP: You need old tires to build an Earthship…
Float home
COST SAVINGS: $200,000 cheaper than some Vancouver condos
WHO IT’S FOR: Home buyers who want a piece of Vancouver shoreline, but can’t stomach a million-dollar mortgage
WHO IT ISN’T FOR: People with mobility issues or who don’t like the idea of shovelling their roof
HOT TIP: If you don’t want to pump out your septic tank each month you can pay the marina about $10 to do it
Cottage escape
COST SAVINGS: Considerable, especially if you steer clear of vacation hotspots
WHO IT’S FOR: The self-employed
WHO IT ISN’T FOR: People who can’t stand the thought of weekend cottage traffic
HOT TIP: Older cottages are often sold “contents-in” which means that you may inherit old love letters from a bygone era or a crocheted wall plaque
Build an Earthship
COST SAVINGS: Huge. You can build for about $25 per square foot
WHO IT’S FOR: Hands-on builders and those who don’t mind lots of digging
WHO IT ISN’T FOR: Anyone who hates the idea of living in Yoda’s Dagobah home
HOT TIP: You need old tires to build an Earthship…
Canada’s “New” Largest Brokerage
– canadianmortgagetrends.com
There’s a race underway in the broker industry, a race for scale. Brokerage firms are uniting to achieve better economies in a shrinking margin environment. And the mega-network trend is fast becoming a three-horse race, with DLC, Group Multi-Prêts Mortgage Alliance (GMP) and VERICO being the volume leaders, in that order. Earlier this month GMP announced that it had narrowed the gap with volume front-runner DLC by purchasing 100% of Invis and its sister company Mortgage Intelligence. That purchase made Group Multi-Prêts Mortgage Alliance the largest full-service brokerage operation in Canada with 3,000 brokers and loan volume of $22 billion annually. (DLC says its run rate is $39 billion this year.) READ MORE
1-in-6 High-Ratio Buyers Could be Benched
– canadianmortgagetrends.com
Based on CMHC’s debt ratio distribution, up to 15-20% of high-ratio buyers may no longer qualify for the same home they could buy yesterday. Maybe more. That’s because today’s new mortgage qualifying rate (MQR) policy could push them above the 39% GDS limit. Many young buyers will now be riding pine until they scrape together a bigger down payment, get a raise, settle for up to an ~18% cheaper home or find a co-buyer. Thankfully, the feds did add one key exception for buyers who already have a firm purchase agreement, dated Oct. 16 or before. That would theoretically exempt folks, for example, who bought on pre-sale READ MORE

