
How to go about securing the best Retirement Plan in Canada.
Latest News


What is RetireMint? The Canadian online platform shows retirement planning isn’t just about finances Sep 27th
I have to admit that when I first heard about RetireMint, it was the clever name that initially got my attention. At first glance, it seems like a misspelling of the ubiquitous term retirement. However, those who follow personal finance news and use the numerous tools and apps devoted to it will pro.... More »
How much should I have in my RRSP? + MORE Feb 22nd
For many Canadians, investing in their registered retirement savings plan (RRSP) is the primary way they save for retirement. RRSPs are an invaluable tool, allowing you to stow away funds for golden years while reducing your taxable income today. However, there is no one-size-fits-all way to use the.... More »
Reality-testing your financial plan + MORE Mar 16th
Q. I am contemplating changing financial planners and I just met with one who seemed very impressive. Within about three hours he had everything laid out for me: the investments I should purchase, the use of life insurance, delaying CPP to 70 and more. Still, I would like to get a second opinion bef.... More »
Should you borrow to pay expenses on an investment property? + MORE Nov 18th
Q. I have an investment property that I rent out. Now that I’m retired, I would like to use the income to supplement my retirement income. That would leave me with no money to pay the expenses on the property (mortgage payment, maintenance, utilities, etc.).
I’m wondering two things: One, can I .... More »
In the years leading up to retirement, an updated financial plan is key: Experts + MORE Jun 29th
Retirement planning getting you down? There are always smart ways to plan the financial aspects of your retirement.
In the years leading up to retirement, an updated financial plan is key: Experts - thestar.comContinue Reading On thestar.com »
How to become a digital nomad—and not g.... More »
How does a mortgage inside an RRSP work?
– moneysense.ca
Q: Is it possible to arrange a mortgage inside my RRSP, so the interest payments are paid back to me?
A: I love the question, but recommend you pursue a less risky hobby. Say, axe throwing or BASE jumping? Setting up your mortgage inside an RRSP requires a lot of work with low return, says Joe Jacobs of Mortgage Connections in Calgary. He points out that “a self-funded mortgage through an RRSP has to be insured by Canada Mortgage and Housing Corp. the plan administrator will also charge set-up and ongoing fees.” You’ll also need to charge commercial interest rates on the mortgage, so the return on your self-funded mortgage will be limited to 3% or 4%. Compare this to what you could earn over the long haul if your RRSP funds were invested in equities and you’re not much further ahead. Now, if you’re interested in reducing your non-deductible debt you could focus on paying down your mortgage. Or you could try using the Smith Manoeuvre, a method of making your mortgage debt a deductible investment loan…
A: I love the question, but recommend you pursue a less risky hobby. Say, axe throwing or BASE jumping? Setting up your mortgage inside an RRSP requires a lot of work with low return, says Joe Jacobs of Mortgage Connections in Calgary. He points out that “a self-funded mortgage through an RRSP has to be insured by Canada Mortgage and Housing Corp. the plan administrator will also charge set-up and ongoing fees.” You’ll also need to charge commercial interest rates on the mortgage, so the return on your self-funded mortgage will be limited to 3% or 4%. Compare this to what you could earn over the long haul if your RRSP funds were invested in equities and you’re not much further ahead. Now, if you’re interested in reducing your non-deductible debt you could focus on paying down your mortgage. Or you could try using the Smith Manoeuvre, a method of making your mortgage debt a deductible investment loan…
Finding the right cover
– moneysense.ca
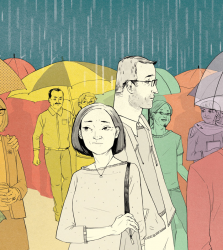 (Illustration by Taryn Gee)
When finance professor Moshe Milevsky teaches insurance to a new group of students, he shows the class a picture of two people, a 30-year-old and a 70-year-old, then asks: “Who needs more life insurance?” The near-term chance of dying is higher for the 70-year-old so, without fail, most students point to the senior.
Which is the wrong answer. The need for life insurance is based on the probability of a dire financial event, but “it’s the small probability that creates the need for insurance, not the high probability,” says Milevsky, who teaches at York University’s Schulich School of Business. As you can see, insurance principles can be somewhat counter-intuitive. That means it’s easy to misunderstand where insurance makes sense and where it doesn’t. As a result, you should think through your insurance needs carefully and critically. That’s especially important at retirement, where other types of insurance needs change significantly. In what follows, we’ll review key insurance products (excluding basic products such as home, auto and travel insurance) and gauge their appropriateness in retirement…
 Canada’s finance ministers are meeting again to discuss CPP expansion. Here are answers to common questions about the plan.
Build a portfolio you can ‘set and forget’
– moneysense.ca
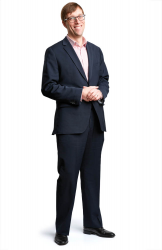 Ian Nelson, 37, Toronto (Photograph by Roberto Caruso)
The Problem
Ian Nelson is a 37-year-old married father of two from Toronto who has spent the last several years paying off the mortgage on his $750,000 home and adding to his retirement savings. Right now, he has a six-figure portfolio invested solely in RRSPs that includes several Canadian stocks as well as three mutual funds, a handful of exchange-traded funds (ETFs), GICs and $16,000 in cash. Now, he’s looking for a well-diversified portfolio that’s low-cost and low-maintenance. “I invest $5,500 quarterly into RRSPs and expect to do this until retirement at age 55. I want to simply buy and hold.”
It’s no small feat to create a low-fee portfolio that doesn’t require annual rebalancing, says Miles Clyne, a portfolio manager with the Tycuda Group at MacDougall Investment Counsel Inc., in Langley, B.C. “But it can be done.”
The Fix
To get the asset allocation and diversification Nelson needs, Clyne recommends that he build his portfolio using two of the four ETFs that make up the iShares Portfolio Builders series of funds: the Conservative Core fund (XCR) and the Global Completion fund (XGC)…

