

Best high-interest savings accounts in Canada 2022 + MORE Oct 5th

How much money do you need to retire in Canada? Is it really $1.7 million? + MORE Mar 1st

CPPIB using its shareholder votes to push for more women on corporate boards: CEO + MORE Nov 11th
Slashing debt is Canadians’ number one priority in 2018 + MORE Dec 30th
Retirement Income for Life: Why Canadian retirees love Frederick Vettese’s books and his PERC + MORE Feb 22nd
Planning for the Worst: Financially Surviving Life-threatening Illness
– rhondasherwood.com
You’ve been busy planning for retirement, and you’re thinking that 65 seems doable but 60 would be even better. The house is paid off, the kids have finally moved out, and mom and dad are happily cared for in a retirement home. Retirement is looking good.
You followed your financial advisor’s advice to be debt-free as soon as possible and then redirected those mortgage payments toward your retirement savings. With even moderate growth and with your pension income you will have the necessary cash flow to fund your basic expenses and lifestyle costs when you are 60. You are only 48 years old now.
You’ve even made extra provisions to ensure you do not outlive your money by planning to save enough between now and retirement to cover your basic costs until age 100. So unless something significant happens, you don’t have any more retirement worries….
WHAM!!! You have been diagnosed with a serious illness – Something you didn’t take into account when you did your retirement planning…
Is an Individual Pension Plan right for you?
– moneysense.ca
 Getty Images
A few weeks ago, we looked at the topic of raising RRSP limits. As noted then, it was based on a C.D. Howe Institute report that suggested one possible solution to the alleged retirement crisis was simply to go back to the half-century-plus RRSP and raise contribution limits for the (relatively) few affluent people who are forced to save in taxable accounts because they’ve maxed out on RRSP room.
If you’re at top executive or own your own business and are 40 years of age or older, there may be another way to get the benefits of RRSPs. The Individual Pension Plan or IPP is an employer-provided program that replaces RRSP savings by an employee, says Stephen Cheng, managing director of Vancouver-based Westcoast Actuaries Inc. To be eligible for an IPP, you need to receive pension-eligible T-4 employment income. Self-employment income, partnership income and dividend income are not pension-eligible, Cheng says. So if you own your own business, you’d have to pay yourself a regular salary that generates T-4 employment income…
Why the 4% withdrawal rule may not be safe
– moneysense.ca
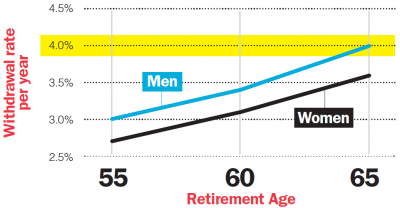 Retirement expert Moshe Milevsky hates the 4% rule. The decades-old maxim states that you can withdraw 4% of your nest egg each year after you retire and you’ll never run out of money. But Milevsky says for most individuals, it’s just not true. Sure, if you’re male, you retire right at 65 and you’re completely average, then it applies, he says. “But what’s average?” The rule doesn’t apply to women at all, he notes, because they live longer, so they’re more likely to run out. As the chart below shows, “average” women should instead budget for 3.6% or less to be safe.
Assumptions: Initial withdrawals are increased annually for inflation. Portfolio is invested 50% in stocks and 50% in bonds, and the inflation rate is 2%. Source: M. Milevsky and F. Habib, CANNEX
The post Why the 4% withdrawal rule may not be safe appeared first on MoneySense.
When investment fees are—and aren’t—worth it
– moneysense.ca
 Q: I am investing with a new bank-owned brokerage, but the fees seem to be higher than I expected. I’ve recently transferred my investments from a group plan through my previous employer. My current MER is around 2%, which may have a big impact on my yearly returns. Any ideas or suggestions to save on fees?—Mauriusz
A: I’m not surprised that you’re suffering from fee shock, Mauriusz. Group plans tends to have pretty low fees—as long as your company’s pension consultant is a good one—and retail investment fees are usually higher by comparison.
Sometimes people are reluctant to transfer money out of their group plans as a result and I don’t blame them. That said, group plans generally have fewer investment choices and they range from bad to good and everything in between, so transferring certainly offers more investment options and control.
In your case, you’re gone now and you’re tasked with evaluating your current options through the bank. Fees of 2% may be high or low, depending on how you are invested and what you are getting…

